Electronic WhatsApp evidence without authentication or independent corroboration cannot sustain an unexplained-investment addition based on third-part...
Page of 4888
Press 'Enter' after typing page number.
1381 to 1400 of 97750 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
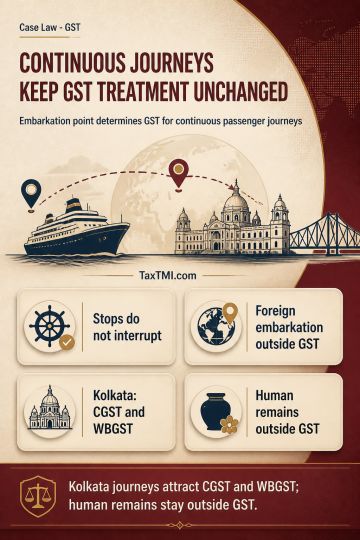
Passenger transportation follows the place of embarkation for a continuous journey. Where either the supplier or passenger is outside India, a short transit stop does not amount to a stopover or interrupt the journey; transportation embarking outside India consequently has a place of supply outside India and is not subject to GST. Where both supplier and passenger are in India, embarkation from Kolkata makes the service an intra-State supply liable to CGST and WBGST at the notified rate, with economy-class treatment subject to the input tax credit condition. Air transportation of human remains falls within funeral, burial, crematorium or mortuary services and is neither a supply of goods nor services, so remains outside GST.
Passenger transportation follows the place of embarkation for a continuous journey. Where either the supplier or passenger is outside India, a short transit stop does not amount to a stopover or interrupt the journey; transportation embarking outside India consequently has a place of supply outside India and is not subject to GST. Where both supplier and passenger are in India, embarkation from Kolkata makes the service an intra-State supply liable to CGST and WBGST at the notified rate, with economy-class treatment subject to the input tax credit condition. Air transportation of human remains falls within funeral, burial, crematorium or mortuary services and is neither a supply of goods nor services, so remains outside GST.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4888