Section 270AA penalty immunity requires identified statutory defaults and a hearing before rejection; reassessment disclosure may constitute under-rep...
Section 80JJAA employee-cost deduction allowed for deployed staff but barred against transfer-pricing income enhancement, with pricing issues remanded...
Transfer-pricing methodology protects commercially genuine associated-enterprise payments, while pre-2016 secondary adjustments and related notional i...
Negative liens over operating assets can constitute international transactions requiring arm's-length pricing reflecting restricted borrowing and expa...
Cross-examination rights in Customs Broker revocation inquiries require witness examination; procedural denial may be cured through fresh adjudication...
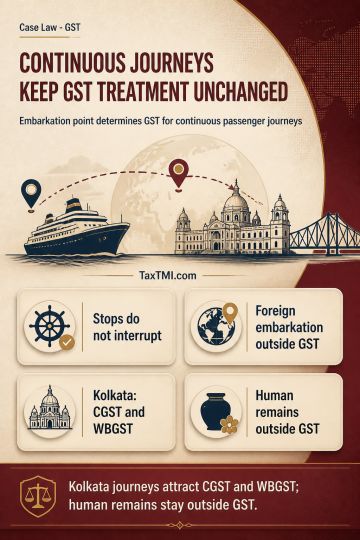
Passenger transportation follows the place of embarkation for a continuous journey. Where either the supplier or passenger is outside India, a short transit stop does not amount to a stopover or interrupt the journey; transportation embarking outside India consequently has a place of supply outside India and is not subject to GST. Where both supplier and passenger are in India, embarkation from Kolkata makes the service an intra-State supply liable to CGST and WBGST at the notified rate, with economy-class treatment subject to the input tax credit condition. Air transportation of human remains falls within funeral, burial, crematorium or mortuary services and is neither a supply of goods nor services, so remains outside GST.
Passenger transportation follows the place of embarkation for a continuous journey. Where either the supplier or passenger is outside India, a short transit stop does not amount to a stopover or interrupt the journey; transportation embarking outside India consequently has a place of supply outside India and is not subject to GST. Where both supplier and passenger are in India, embarkation from Kolkata makes the service an intra-State supply liable to CGST and WBGST at the notified rate, with economy-class treatment subject to the input tax credit condition. Air transportation of human remains falls within funeral, burial, crematorium or mortuary services and is neither a supply of goods nor services, so remains outside GST.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4886