Donor-directed corpus contributions retain capital character despite exemption claims under section 10(23C)(vi), preventing their treatment as taxable...
Enhanced tax-audit threshold applies where banking records establish compliant non-cash receipts and payments, eliminating penalty exposure for audit ...
Transfer pricing consistency protects identical non-interest-bearing debenture terms from a later notional-interest adjustment without valid statutory...
Rectification of debatable deduction claims cannot reverse scrutiny-approved co-operative society interest income deductions as apparent record errors...
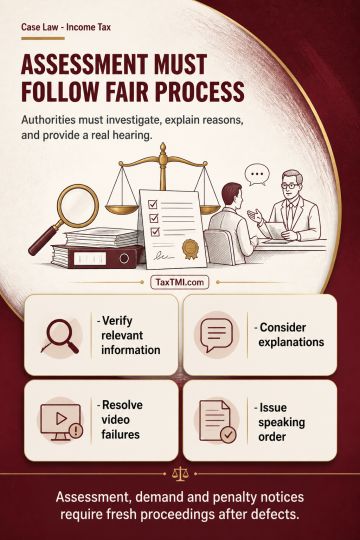
Faceless assessment procedure requires necessary enquiry, verification and collection of relevant information before issuing a show cause notice, with reasoned consideration of explanations and reconciliations. Blanket notices and additions that disregard disclosed Category III AIF redemption proceeds or explained unlisted-share sale proceeds, including reliance on unrequested purchaser-source details, demonstrate arbitrariness and non-application of mind. Effective personal hearing is also required: a same-day hearing notice and an unresolved video-conference failure deny natural justice. These defects vitiated the assessment, consequential demand and penalty notices, requiring fresh proceedings, a hearing on at least five working days' notice before any adverse order, and a speaking, reasoned order.
Faceless assessment procedure requires necessary enquiry, verification and collection of relevant information before issuing a show cause notice, with reasoned consideration of explanations and reconciliations. Blanket notices and additions that disregard disclosed Category III AIF redemption proceeds or explained unlisted-share sale proceeds, including reliance on unrequested purchaser-source details, demonstrate arbitrariness and non-application of mind. Effective personal hearing is also required: a same-day hearing notice and an unresolved video-conference failure deny natural justice. These defects vitiated the assessment, consequential demand and penalty notices, requiring fresh proceedings, a hearing on at least five working days' notice before any adverse order, and a speaking, reasoned order.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4897