TNMM functional comparability requires excluding rice manufacturers from a pure Basmati rice trader's benchmark and recognising operating export recei...
Working-capital adjustment subsumes delayed-receivable effects in TNMM benchmarking of captive software-development services, avoiding separate notion...
Transfer-pricing comparability requires exclusion of financially illogical super-profit comparables and correction of unsupported annual-report and ma...
Charitable character assessment preserves Section 80G approval despite inclusive spiritual teachings and incidental religious expenditure within the s...
Penalty proceedings for cash-loan acceptance require assessment proceedings and recorded Assessing Officer satisfaction; absent these, the proceedings...
Functional comparability governs software-service benchmarking: dissimilar companies are excluded, while related-party filters, margins and working-ca...
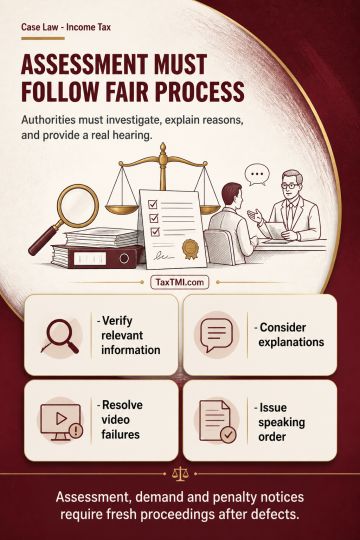
Faceless assessment procedure requires necessary enquiry, verification and collection of relevant information before issuing a show cause notice, with reasoned consideration of explanations and reconciliations. Blanket notices and additions that disregard disclosed Category III AIF redemption proceeds or explained unlisted-share sale proceeds, including reliance on unrequested purchaser-source details, demonstrate arbitrariness and non-application of mind. Effective personal hearing is also required: a same-day hearing notice and an unresolved video-conference failure deny natural justice. These defects vitiated the assessment, consequential demand and penalty notices, requiring fresh proceedings, a hearing on at least five working days' notice before any adverse order, and a speaking, reasoned order.
Faceless assessment procedure requires necessary enquiry, verification and collection of relevant information before issuing a show cause notice, with reasoned consideration of explanations and reconciliations. Blanket notices and additions that disregard disclosed Category III AIF redemption proceeds or explained unlisted-share sale proceeds, including reliance on unrequested purchaser-source details, demonstrate arbitrariness and non-application of mind. Effective personal hearing is also required: a same-day hearing notice and an unresolved video-conference failure deny natural justice. These defects vitiated the assessment, consequential demand and penalty notices, requiring fresh proceedings, a hearing on at least five working days' notice before any adverse order, and a speaking, reasoned order.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4886