Charitable trust registration requires a specified-violation notice; settled cash deposits and related-party payments did not justify cancellation or ...
External development charges trigger TDS under section 194C, while disputed administrative payments require factual verification and fresh adjudicatio...
Section 270AA penalty immunity requires identified statutory defaults and a hearing before rejection; reassessment disclosure may constitute under-rep...
Section 80JJAA employee-cost deduction allowed for deployed staff but barred against transfer-pricing income enhancement, with pricing issues remanded...
Transfer-pricing methodology protects commercially genuine associated-enterprise payments, while pre-2016 secondary adjustments and related notional i...
Negative liens over operating assets can constitute international transactions requiring arm's-length pricing reflecting restricted borrowing and expa...
Page of 4886
Press 'Enter' after typing page number.
1261 to 1280 of 97705 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
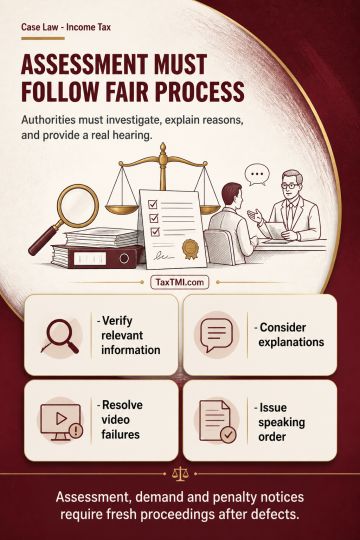
Faceless assessment procedure requires necessary enquiry, verification and collection of relevant information before issuing a show cause notice, with reasoned consideration of explanations and reconciliations. Blanket notices and additions that disregard disclosed Category III AIF redemption proceeds or explained unlisted-share sale proceeds, including reliance on unrequested purchaser-source details, demonstrate arbitrariness and non-application of mind. Effective personal hearing is also required: a same-day hearing notice and an unresolved video-conference failure deny natural justice. These defects vitiated the assessment, consequential demand and penalty notices, requiring fresh proceedings, a hearing on at least five working days' notice before any adverse order, and a speaking, reasoned order.
Faceless assessment procedure requires necessary enquiry, verification and collection of relevant information before issuing a show cause notice, with reasoned consideration of explanations and reconciliations. Blanket notices and additions that disregard disclosed Category III AIF redemption proceeds or explained unlisted-share sale proceeds, including reliance on unrequested purchaser-source details, demonstrate arbitrariness and non-application of mind. Effective personal hearing is also required: a same-day hearing notice and an unresolved video-conference failure deny natural justice. These defects vitiated the assessment, consequential demand and penalty notices, requiring fresh proceedings, a hearing on at least five working days' notice before any adverse order, and a speaking, reasoned order.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4886