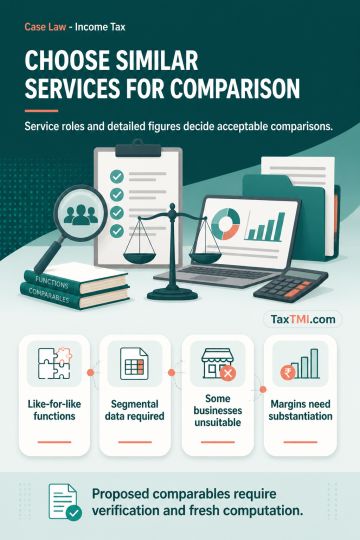
Functional comparability under TNMM supported exclusion of ITeS comparables with R&D, intangibles, diversified operations, or unavailable segmental da...
Functional comparability governs selection of support-service and IT-enabled service comparables, with verification required for unresolved data and m...
Page of 4888
Press 'Enter' after typing page number.
1421 to 1440 of 97755 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
The proviso to Section 276CC bars prosecution for failure to furnish an income-tax return where tax payable on total income determined on regular assessment, after reducing advance tax and tax deducted at source, does not exceed the prescribed threshold. Where no tax remains due and tax deducted at source exceeds the assessed liability, delayed filing cannot sustain prosecution. On these facts, continuation of criminal proceedings constituted an abuse of process and the prosecution was quashed.
The proviso to Section 276CC bars prosecution for failure to furnish an income-tax return where tax payable on total income determined on regular assessment, after reducing advance tax and tax deducted at source, does not exceed the prescribed threshold. Where no tax remains due and tax deducted at source exceeds the assessed liability, delayed filing cannot sustain prosecution. On these facts, continuation of criminal proceedings constituted an abuse of process and the prosecution was quashed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4888