Automated Free Sale and Commerce Certificates enable paperless processing while retaining risk-based manual verification for selected exporter applica...
Employee stock-shortage penalties do not constitute consideration for services, preventing GST collection under Schedule II in employment relationship...
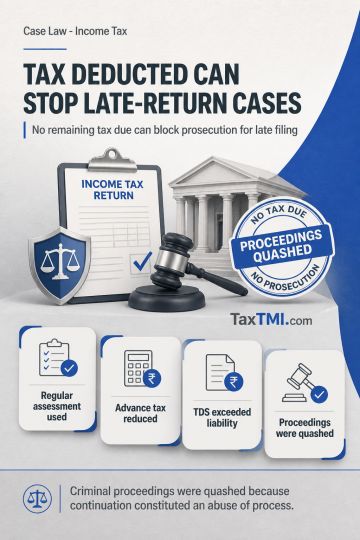
The proviso to Section 276CC bars prosecution for failure to furnish an income-tax return where tax payable on total income determined on regular assessment, after reducing advance tax and tax deducted at source, does not exceed the prescribed threshold. Where no tax remains due and tax deducted at source exceeds the assessed liability, delayed filing cannot sustain prosecution. On these facts, continuation of criminal proceedings constituted an abuse of process and the prosecution was quashed.
The proviso to Section 276CC bars prosecution for failure to furnish an income-tax return where tax payable on total income determined on regular assessment, after reducing advance tax and tax deducted at source, does not exceed the prescribed threshold. Where no tax remains due and tax deducted at source exceeds the assessed liability, delayed filing cannot sustain prosecution. On these facts, continuation of criminal proceedings constituted an abuse of process and the prosecution was quashed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4886