Electronic WhatsApp evidence without authentication or independent corroboration cannot sustain an unexplained-investment addition based on third-part...
Page of 4886
Press 'Enter' after typing page number.
1341 to 1360 of 97710 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
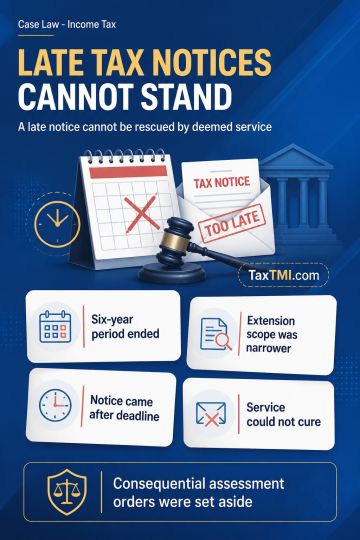
Reassessment notices under Section 148 must be issued within the applicable limitation period. The original six-year period expired on 31 March 2020, while the relevant extension notification covered only notices whose original limitation expired on 31 March 2021; it therefore did not extend time for a notice issued on 1 April 2021. Such notice was time-barred, requiring the consequential assessment orders to be set aside. Section 292BB addresses defects in service where an assessee participates in proceedings despite ineffective service; it cannot validate a reassessment notice issued after the statutory limitation period.
Reassessment notices under Section 148 must be issued within the applicable limitation period. The original six-year period expired on 31 March 2020, while the relevant extension notification covered only notices whose original limitation expired on 31 March 2021; it therefore did not extend time for a notice issued on 1 April 2021. Such notice was time-barred, requiring the consequential assessment orders to be set aside. Section 292BB addresses defects in service where an assessee participates in proceedings despite ineffective service; it cannot validate a reassessment notice issued after the statutory limitation period.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4886