Authorised courier due diligence protects against penalties where declared exports conceal prohibited goods despite proper documentation and customs p...
Customs-controlled container movement now extends to DP World facilities, subject to segregation, inspections, reconciliation, and EXIM cargo priority...
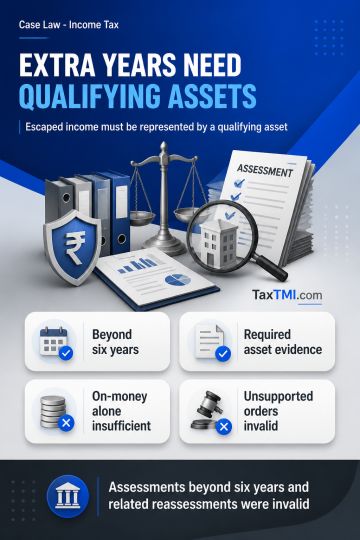
The extended period beyond six assessment years for a search assessment under the fourth proviso to section 153A(1) applies only where material available to the Assessing Officer shows escaped income represented by a stipulated asset of the required value. Alleged on-money receipts from project buyers, without a finding that those receipts were represented by such an asset, do not meet that condition. Assessments initiated beyond the six-year period on that basis were void ab initio, and the consequential reassessment orders for the relevant years were invalid.
The extended period beyond six assessment years for a search assessment under the fourth proviso to section 153A(1) applies only where material available to the Assessing Officer shows escaped income represented by a stipulated asset of the required value. Alleged on-money receipts from project buyers, without a finding that those receipts were represented by such an asset, do not meet that condition. Assessments initiated beyond the six-year period on that basis were void ab initio, and the consequential reassessment orders for the relevant years were invalid.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4886