Transfer-pricing comparability requires exclusion of financially illogical super-profit comparables and correction of unsupported annual-report and ma...
Charitable character assessment preserves Section 80G approval despite inclusive spiritual teachings and incidental religious expenditure within the s...
Penalty proceedings for cash-loan acceptance require assessment proceedings and recorded Assessing Officer satisfaction; absent these, the proceedings...
Functional comparability governs software-service benchmarking: dissimilar companies are excluded, while related-party filters, margins and working-ca...
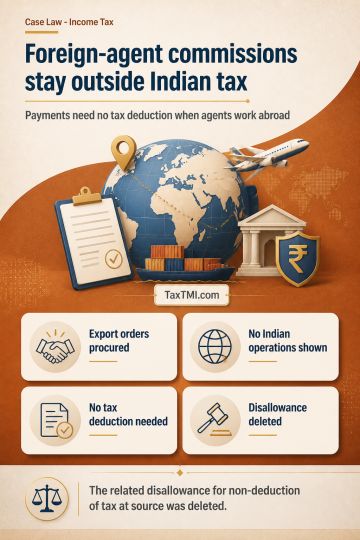
Commission paid to non-resident agents for procuring export orders through services rendered outside India is not chargeable to tax in India merely because it relates to an Indian exporter's business. Tax deduction at source on such payments arises only where the income is chargeable to tax in India. In the absence of material showing that the agents rendered services in India or maintained a permanent establishment or business operations in India, the commission remains outside Indian tax charge. Consequently, no tax was deductible on the foreign commission payments, and the corresponding disallowance for non-deduction of tax at source was deleted.
Commission paid to non-resident agents for procuring export orders through services rendered outside India is not chargeable to tax in India merely because it relates to an Indian exporter's business. Tax deduction at source on such payments arises only where the income is chargeable to tax in India. In the absence of material showing that the agents rendered services in India or maintained a permanent establishment or business operations in India, the commission remains outside Indian tax charge. Consequently, no tax was deductible on the foreign commission payments, and the corresponding disallowance for non-deduction of tax at source was deleted.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4934