Agricultural land classification requires cumulative factual indicators, while industrial-purpose land and absent agricultural use defeat reinvestment...
Composite residential flat exemption upheld where supplementary agreement merged adjoining units and additional evidence supported the taxpayer's inve...
Urgent interim relief exception permits commercial suit without pre-institution mediation where immediate disclosure and asset protection are genuinel...
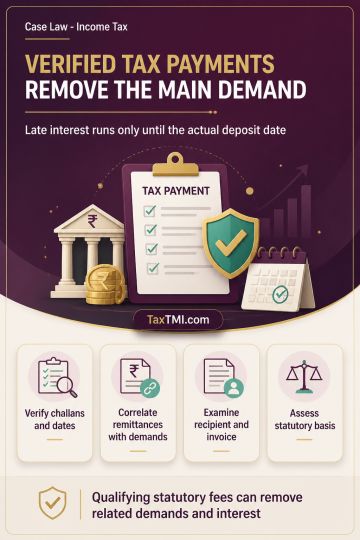
Tax deducted at source that is subsequently deposited into the Government Treasury should not remain recoverable as principal TDS liability once the remittance is verified. Interest for delayed remittance continues to apply, but only up to the actual date of deposit; challans, payment dates and correlation with the demand require verification before recomputation. Renewable Energy Certificate registration charges require examination of the payment's nature, recipient, supporting invoice or demand, and statutory basis. Where the charges qualify as statutory or registration fees not subject to TDS, the related demand and interest should be deleted; otherwise, liability must be determined under the applicable law.
Tax deducted at source that is subsequently deposited into the Government Treasury should not remain recoverable as principal TDS liability once the remittance is verified. Interest for delayed remittance continues to apply, but only up to the actual date of deposit; challans, payment dates and correlation with the demand require verification before recomputation. Renewable Energy Certificate registration charges require examination of the payment's nature, recipient, supporting invoice or demand, and statutory basis. Where the charges qualify as statutory or registration fees not subject to TDS, the related demand and interest should be deleted; otherwise, liability must be determined under the applicable law.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4891