Equivalent-value attachment survives prior release and environmental compensation where deposits may represent proceeds from alleged illegal mining ac...
Withdrawal of obsolete FEMA circulars streamlines rules on external commercial borrowings, non-resident bond investments, and money transfer sub-agent...
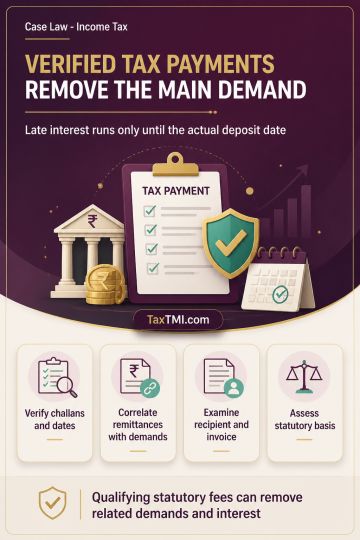
Tax deducted at source that is subsequently deposited into the Government Treasury should not remain recoverable as principal TDS liability once the remittance is verified. Interest for delayed remittance continues to apply, but only up to the actual date of deposit; challans, payment dates and correlation with the demand require verification before recomputation. Renewable Energy Certificate registration charges require examination of the payment's nature, recipient, supporting invoice or demand, and statutory basis. Where the charges qualify as statutory or registration fees not subject to TDS, the related demand and interest should be deleted; otherwise, liability must be determined under the applicable law.
Tax deducted at source that is subsequently deposited into the Government Treasury should not remain recoverable as principal TDS liability once the remittance is verified. Interest for delayed remittance continues to apply, but only up to the actual date of deposit; challans, payment dates and correlation with the demand require verification before recomputation. Renewable Energy Certificate registration charges require examination of the payment's nature, recipient, supporting invoice or demand, and statutory basis. Where the charges qualify as statutory or registration fees not subject to TDS, the related demand and interest should be deleted; otherwise, liability must be determined under the applicable law.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4891