Bogus-purchase additions are limited to embedded profit where corresponding sales are accepted, while accommodation-entry information can support reas...
Provisional attachment fails without material showing likely concealment, transfer, or dealing that could frustrate confiscation of mortgaged property...
Works-contract goods transfers remain outside service tax, while qualifying lift irrigation works receive exemption and extended limitation cannot app...
Page of 4888
Press 'Enter' after typing page number.
1141 to 1160 of 97755 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
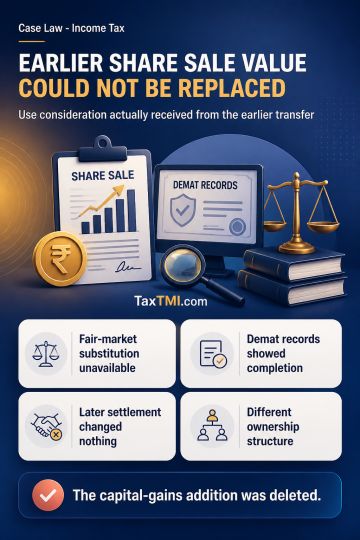
Capital-gains computation for an unquoted equity-share transfer uses the consideration actually received or accruing from that transfer; a notional value may replace it only under an express statutory fiction. The prescribed fair-market-value substitution did not apply where the declared consideration exceeded fair market value. Demat records and contemporaneous delivery instructions established completion of the earlier transfer, and later settlement of the purchaser's liability could not alter its transfer date or consideration. A subsequent transfer under a different ownership and contractual structure could not substitute its consideration for the earlier transaction, particularly where conditions had not crystallised the final price. The capital-gains addition was therefore deleted.
Capital-gains computation for an unquoted equity-share transfer uses the consideration actually received or accruing from that transfer; a notional value may replace it only under an express statutory fiction. The prescribed fair-market-value substitution did not apply where the declared consideration exceeded fair market value. Demat records and contemporaneous delivery instructions established completion of the earlier transfer, and later settlement of the purchaser's liability could not alter its transfer date or consideration. A subsequent transfer under a different ownership and contractual structure could not substitute its consideration for the earlier transaction, particularly where conditions had not crystallised the final price. The capital-gains addition was therefore deleted.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4888