Prospective customs notification amendments cannot bar provisional release consideration for earlier imports when bills of lading predate their commen...
Personal guarantor insolvency jurisdiction follows the corporate debtor's CIRP Bench, enabling inter-territorial transfer and preventing parallel proc...
Section 47-A undervaluation threshold: fraudulent intent requirement faces reconsideration after referral to a larger Bench for authoritative resoluti...
RBI supersession powers over multi-State co-operative banks operate independently of the constitutional six-month ceiling and permit statutory extensi...
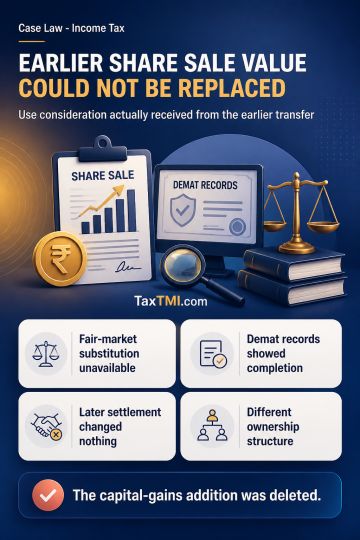
Capital-gains computation for an unquoted equity-share transfer uses the consideration actually received or accruing from that transfer; a notional value may replace it only under an express statutory fiction. The prescribed fair-market-value substitution did not apply where the declared consideration exceeded fair market value. Demat records and contemporaneous delivery instructions established completion of the earlier transfer, and later settlement of the purchaser's liability could not alter its transfer date or consideration. A subsequent transfer under a different ownership and contractual structure could not substitute its consideration for the earlier transaction, particularly where conditions had not crystallised the final price. The capital-gains addition was therefore deleted.
Capital-gains computation for an unquoted equity-share transfer uses the consideration actually received or accruing from that transfer; a notional value may replace it only under an express statutory fiction. The prescribed fair-market-value substitution did not apply where the declared consideration exceeded fair market value. Demat records and contemporaneous delivery instructions established completion of the earlier transfer, and later settlement of the purchaser's liability could not alter its transfer date or consideration. A subsequent transfer under a different ownership and contractual structure could not substitute its consideration for the earlier transaction, particularly where conditions had not crystallised the final price. The capital-gains addition was therefore deleted.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4891