Customs Broker due diligence requires prescribed KYC, not detecting misdeclarations discoverable only through physical examination, defeating licence ...
E-filing system failure permits exclusion of affected time in insolvency appeals, preventing tribunal technology defects from defeating timely filings...
Pre-existing disputes over outcome-based professional fees can bar Section 9 insolvency proceedings where contractual entitlement requires investigati...
Corresponding scheduled offences preserve money-laundering jurisdiction despite repeal of the central corruption provision where conduct remains cover...
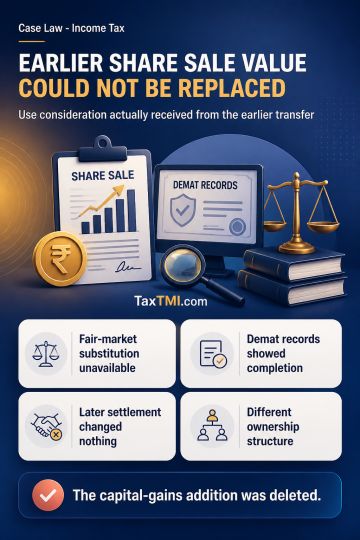
Capital-gains computation for an unquoted equity-share transfer uses the consideration actually received or accruing from that transfer; a notional value may replace it only under an express statutory fiction. The prescribed fair-market-value substitution did not apply where the declared consideration exceeded fair market value. Demat records and contemporaneous delivery instructions established completion of the earlier transfer, and later settlement of the purchaser's liability could not alter its transfer date or consideration. A subsequent transfer under a different ownership and contractual structure could not substitute its consideration for the earlier transaction, particularly where conditions had not crystallised the final price. The capital-gains addition was therefore deleted.
Capital-gains computation for an unquoted equity-share transfer uses the consideration actually received or accruing from that transfer; a notional value may replace it only under an express statutory fiction. The prescribed fair-market-value substitution did not apply where the declared consideration exceeded fair market value. Demat records and contemporaneous delivery instructions established completion of the earlier transfer, and later settlement of the purchaser's liability could not alter its transfer date or consideration. A subsequent transfer under a different ownership and contractual structure could not substitute its consideration for the earlier transaction, particularly where conditions had not crystallised the final price. The capital-gains addition was therefore deleted.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4897