Employee stock-shortage penalties do not constitute consideration for services, preventing GST collection under Schedule II in employment relationship...
Transfer-pricing treatment of ITeS margins excludes pass-through tax recoveries and separate delayed-receivables interest after working-capital adjust...
Capacity-utilisation adjustments under TNMM can neutralise substantiated COVID-related idle costs where underutilisation materially affects profitabil...
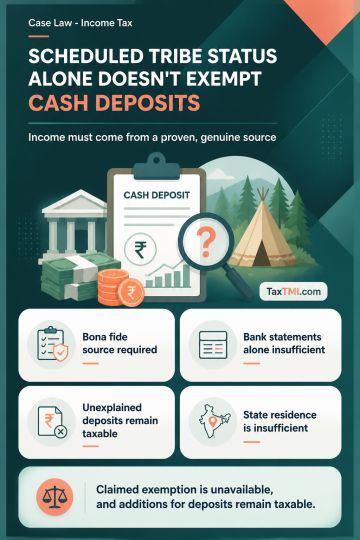
Scheduled Tribe income exemption applies only where the taxpayer establishes income from a valid, bona fide source within the statutory conditions. Cash deposits treated as unexplained money do not become exempt solely because the taxpayer is a Scheduled Tribe member residing in a specified State. Bank statements, without books of account or other evidence establishing the source, are insufficient to prove the character of deposits. Consequently, additions for unexplained cash deposits remain taxable and the claimed exemption is unavailable.
Scheduled Tribe income exemption applies only where the taxpayer establishes income from a valid, bona fide source within the statutory conditions. Cash deposits treated as unexplained money do not become exempt solely because the taxpayer is a Scheduled Tribe member residing in a specified State. Bank statements, without books of account or other evidence establishing the source, are insufficient to prove the character of deposits. Consequently, additions for unexplained cash deposits remain taxable and the claimed exemption is unavailable.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4886