Document Identification Number compliance renders TDS-default orders invalid where mandatory DIN requirements are breached and curative provision does...
Anti-profiteering obligations survive business demerger, complaint withdrawal, and customized supply arrangements where rate-reduction benefits are no...
Road restoration charges constitute taxable services when requested for commercial pipeline activity, requiring reverse-charge GST from the business r...
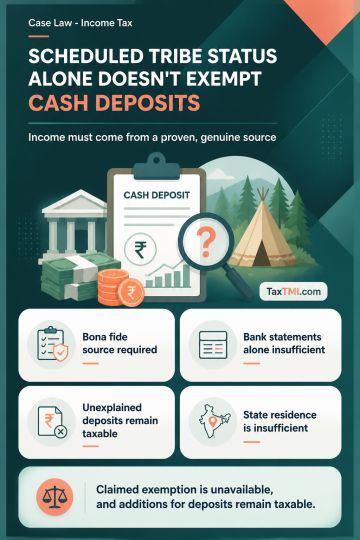
Scheduled Tribe income exemption applies only where the taxpayer establishes income from a valid, bona fide source within the statutory conditions. Cash deposits treated as unexplained money do not become exempt solely because the taxpayer is a Scheduled Tribe member residing in a specified State. Bank statements, without books of account or other evidence establishing the source, are insufficient to prove the character of deposits. Consequently, additions for unexplained cash deposits remain taxable and the claimed exemption is unavailable.
Scheduled Tribe income exemption applies only where the taxpayer establishes income from a valid, bona fide source within the statutory conditions. Cash deposits treated as unexplained money do not become exempt solely because the taxpayer is a Scheduled Tribe member residing in a specified State. Bank statements, without books of account or other evidence establishing the source, are insufficient to prove the character of deposits. Consequently, additions for unexplained cash deposits remain taxable and the claimed exemption is unavailable.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915