Penny-stock additions require transaction-specific evidence; general investigation material alone cannot establish undisclosed income or accommodation...
Transfer pricing comparability prioritises reliable external CUPs and foreign-currency LIBOR benchmarks for exports, borrowings and delayed receivable...
Section 153C satisfaction and seized electronic records sustained unexplained-investment addition, subject to proportionate ownership-share verificati...
Natural justice in insolvency-professional discipline requires disclosed material; notices based on extraneous material and ignored defences are vitia...
Page of 4888
Press 'Enter' after typing page number.
1521 to 1540 of 97755 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
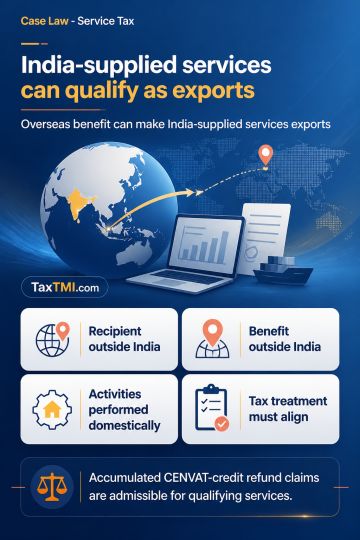
Revenue cannot treat Business Auxiliary Services supplied to a foreign recipient as non-exported for Rule 5 CENVAT-credit refund purposes while not seeking recovery of service tax on the inconsistent premise that those same services were taxable in India. Category III services supplied in relation to business or commerce qualify as exports where the recipient is outside India and the benefit accrues outside India, even if activities are performed in India. Accumulated CENVAT-credit refund claims are therefore admissible for qualifying services.
Revenue cannot treat Business Auxiliary Services supplied to a foreign recipient as non-exported for Rule 5 CENVAT-credit refund purposes while not seeking recovery of service tax on the inconsistent premise that those same services were taxable in India. Category III services supplied in relation to business or commerce qualify as exports where the recipient is outside India and the benefit accrues outside India, even if activities are performed in India. Accumulated CENVAT-credit refund claims are therefore admissible for qualifying services.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4888