Charitable trust registration requires a specified-violation notice; settled cash deposits and related-party payments did not justify cancellation or ...
External development charges trigger TDS under section 194C, while disputed administrative payments require factual verification and fresh adjudicatio...
Section 270AA penalty immunity requires identified statutory defaults and a hearing before rejection; reassessment disclosure may constitute under-rep...
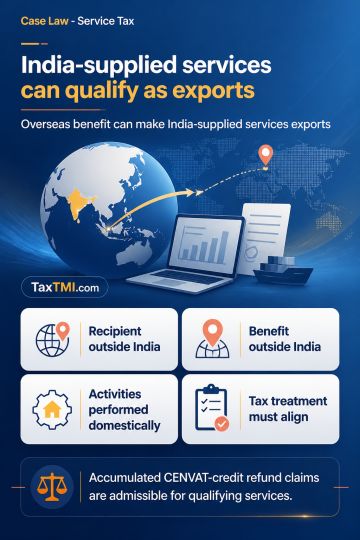
Revenue cannot treat Business Auxiliary Services supplied to a foreign recipient as non-exported for Rule 5 CENVAT-credit refund purposes while not seeking recovery of service tax on the inconsistent premise that those same services were taxable in India. Category III services supplied in relation to business or commerce qualify as exports where the recipient is outside India and the benefit accrues outside India, even if activities are performed in India. Accumulated CENVAT-credit refund claims are therefore admissible for qualifying services.
Revenue cannot treat Business Auxiliary Services supplied to a foreign recipient as non-exported for Rule 5 CENVAT-credit refund purposes while not seeking recovery of service tax on the inconsistent premise that those same services were taxable in India. Category III services supplied in relation to business or commerce qualify as exports where the recipient is outside India and the benefit accrues outside India, even if activities are performed in India. Accumulated CENVAT-credit refund claims are therefore admissible for qualifying services.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4886