Pre-amendment reassessment limitation bars late notices under the preserved regime, invalidating consequential reassessment for affected earlier asses...
Cash-sales explanations for bank deposits require documentary reconciliation; reassessment notice survived where effective response time was available...
Functional comparability in transfer pricing prevents ad hoc arm's length adjustments where functions, assets, risks and reliable comparables are unes...
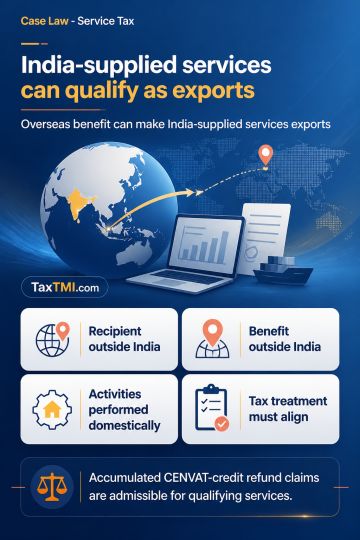
Revenue cannot treat Business Auxiliary Services supplied to a foreign recipient as non-exported for Rule 5 CENVAT-credit refund purposes while not seeking recovery of service tax on the inconsistent premise that those same services were taxable in India. Category III services supplied in relation to business or commerce qualify as exports where the recipient is outside India and the benefit accrues outside India, even if activities are performed in India. Accumulated CENVAT-credit refund claims are therefore admissible for qualifying services.
Revenue cannot treat Business Auxiliary Services supplied to a foreign recipient as non-exported for Rule 5 CENVAT-credit refund purposes while not seeking recovery of service tax on the inconsistent premise that those same services were taxable in India. Category III services supplied in relation to business or commerce qualify as exports where the recipient is outside India and the benefit accrues outside India, even if activities are performed in India. Accumulated CENVAT-credit refund claims are therefore admissible for qualifying services.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918