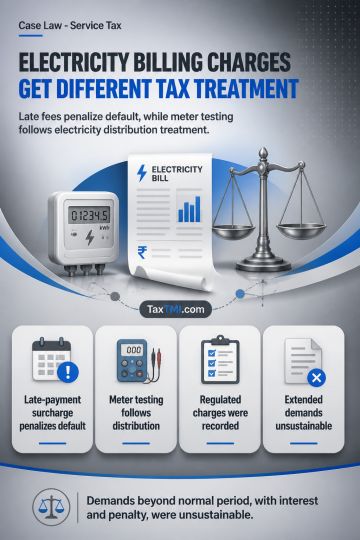
Delayed-payment surcharge is not taxable tolerance consideration where it penalises default, while meter testing follows electricity distribution trea...
Works-contract goods transfers remain outside service tax, while qualifying lift irrigation works receive exemption and extended limitation cannot app...
Governmental authority status supports construction-service exemption, while pre-cutoff contract and stamp-duty compliance requires verification on re...
Original works exemption excludes standalone boulder transportation, leaving subcontracted railway-project transport services subject to service tax l...
Development rights transfers treated as immovable property, while construction abatement applies and repeated non-payment permits extended service-tax...
Page of 481
Press 'Enter' after typing page number.
1 to 20 of 9619 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
Revenue cannot treat Business Auxiliary Services supplied to a foreign recipient as non-exported for Rule 5 CENVAT-credit refund purposes while not seeking recovery of service tax on the inconsistent premise that those same services were taxable in India. Category III services supplied in relation to business or commerce qualify as exports where the recipient is outside India and the benefit accrues outside India, even if activities are performed in India. Accumulated CENVAT-credit refund claims are therefore admissible for qualifying services.
Revenue cannot treat Business Auxiliary Services supplied to a foreign recipient as non-exported for Rule 5 CENVAT-credit refund purposes while not seeking recovery of service tax on the inconsistent premise that those same services were taxable in India. Category III services supplied in relation to business or commerce qualify as exports where the recipient is outside India and the benefit accrues outside India, even if activities are performed in India. Accumulated CENVAT-credit refund claims are therefore admissible for qualifying services.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI