Governmental authority status supports construction-service exemption, while pre-cutoff contract and stamp-duty compliance requires verification on re...
Automated Free Sale and Commerce Certificates enable paperless processing while retaining risk-based manual verification for selected exporter applica...
Employee stock-shortage penalties do not constitute consideration for services, preventing GST collection under Schedule II in employment relationship...
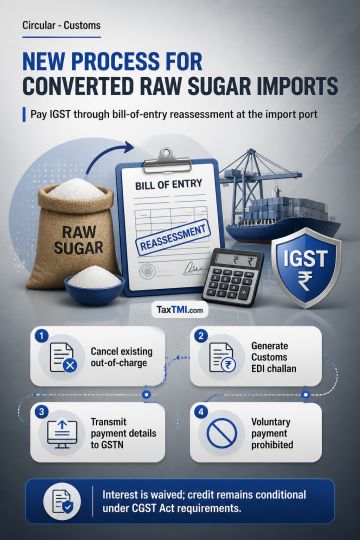
IGST on raw sugar actually imported under the Advance Authorisation Scheme and converted once to the Tariff Rate Quota Scheme must be paid at the port of import through reassessment of the relevant bill of entry. The assessment group must cancel the existing out-of-charge order, reassess the bill of entry to levy tax, and generate an electronic challan in the Customs EDI System. After payment, a notional out-of-charge order must transmit IGST payment details to GSTN. Interest on the IGST payment is waived. Input tax credit remains available only subject to applicable CGST Act eligibility and conditions. Payment through the Voluntary Payment Challan module is prohibited for this process.
IGST on raw sugar actually imported under the Advance Authorisation Scheme and converted once to the Tariff Rate Quota Scheme must be paid at the port of import through reassessment of the relevant bill of entry. The assessment group must cancel the existing out-of-charge order, reassess the bill of entry to levy tax, and generate an electronic challan in the Customs EDI System. After payment, a notional out-of-charge order must transmit IGST payment details to GSTN. Interest on the IGST payment is waived. Input tax credit remains available only subject to applicable CGST Act eligibility and conditions. Payment through the Voluntary Payment Challan module is prohibited for this process.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4886