Governmental authority status supports construction-service exemption, while pre-cutoff contract and stamp-duty compliance requires verification on re...
Automated Free Sale and Commerce Certificates enable paperless processing while retaining risk-based manual verification for selected exporter applica...
Employee stock-shortage penalties do not constitute consideration for services, preventing GST collection under Schedule II in employment relationship...
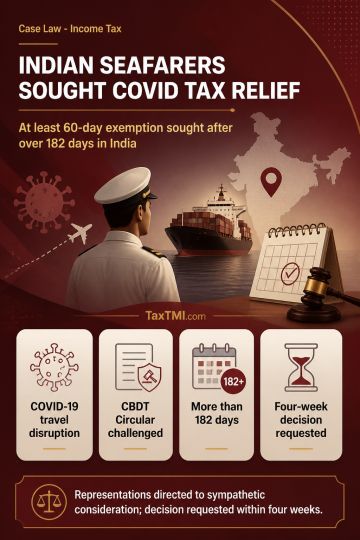
Tax-residency relief for Indian seafarers unable to remain outside India during the COVID-19 pandemic was sought through quashing CBDT Circular No. 11 of 2020 and adoption of a compassionate tax policy. The proposed policy would grant at least sixty days' exemption to seafarers who spent more than 182 days in India during a financial year. Representations were directed to receive sympathetic consideration, with an appropriate decision requested within four weeks, without examination of merits.
Tax-residency relief for Indian seafarers unable to remain outside India during the COVID-19 pandemic was sought through quashing CBDT Circular No. 11 of 2020 and adoption of a compassionate tax policy. The proposed policy would grant at least sixty days' exemption to seafarers who spent more than 182 days in India during a financial year. Representations were directed to receive sympathetic consideration, with an appropriate decision requested within four weeks, without examination of merits.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4886