Electronic WhatsApp evidence without authentication or independent corroboration cannot sustain an unexplained-investment addition based on third-part...
Page of 4886
Press 'Enter' after typing page number.
1341 to 1360 of 97710 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
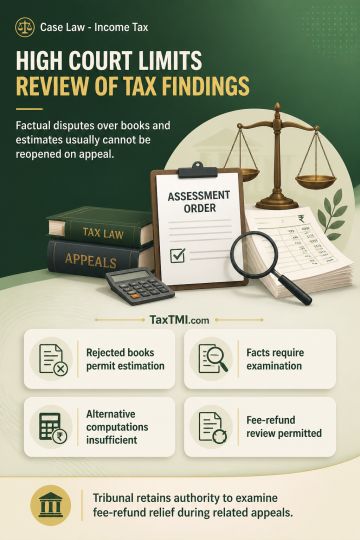
Section 260A confines High Court interference with Tribunal findings on rejection of books, income estimation and fee refunds to cases of perversity, lack of evidentiary support or legal error. Where seized material, account books and submissions require factual examination, alternative computations do not themselves create a substantial question of law. Once books are rejected, income and allowable fee refunds may be determined by estimation. The Tribunal may examine the basis and extent of fee-refund relief when the Revenue challenges that relief and the assessee files a cross-objection concerning the sustained addition; this remains within its appellate jurisdiction.
Section 260A confines High Court interference with Tribunal findings on rejection of books, income estimation and fee refunds to cases of perversity, lack of evidentiary support or legal error. Where seized material, account books and submissions require factual examination, alternative computations do not themselves create a substantial question of law. Once books are rejected, income and allowable fee refunds may be determined by estimation. The Tribunal may examine the basis and extent of fee-refund relief when the Revenue challenges that relief and the assessee files a cross-objection concerning the sustained addition; this remains within its appellate jurisdiction.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4886