Governmental authority status supports construction-service exemption, while pre-cutoff contract and stamp-duty compliance requires verification on re...
Automated Free Sale and Commerce Certificates enable paperless processing while retaining risk-based manual verification for selected exporter applica...
Employee stock-shortage penalties do not constitute consideration for services, preventing GST collection under Schedule II in employment relationship...
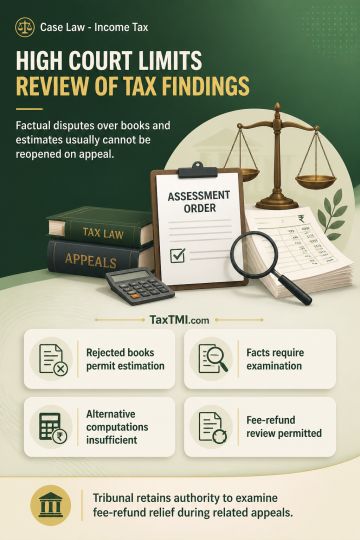
Section 260A confines High Court interference with Tribunal findings on rejection of books, income estimation and fee refunds to cases of perversity, lack of evidentiary support or legal error. Where seized material, account books and submissions require factual examination, alternative computations do not themselves create a substantial question of law. Once books are rejected, income and allowable fee refunds may be determined by estimation. The Tribunal may examine the basis and extent of fee-refund relief when the Revenue challenges that relief and the assessee files a cross-objection concerning the sustained addition; this remains within its appellate jurisdiction.
Section 260A confines High Court interference with Tribunal findings on rejection of books, income estimation and fee refunds to cases of perversity, lack of evidentiary support or legal error. Where seized material, account books and submissions require factual examination, alternative computations do not themselves create a substantial question of law. Once books are rejected, income and allowable fee refunds may be determined by estimation. The Tribunal may examine the basis and extent of fee-refund relief when the Revenue challenges that relief and the assessee files a cross-objection concerning the sustained addition; this remains within its appellate jurisdiction.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4939