Handicraft job work receives concessional GST only for registered principals and predominantly handmade goods; commercial resin articles remain taxabl...
Reassessment disclosure requirements permit stated reasons without revealing information sources, but prior-taxation claims require full examination b...
Independent assessment discretion and corroborated electronic evidence determine validity of on-money additions and undisclosed-consideration assessme...
Page of 4897
Press 'Enter' after typing page number.
1621 to 1640 of 97923 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
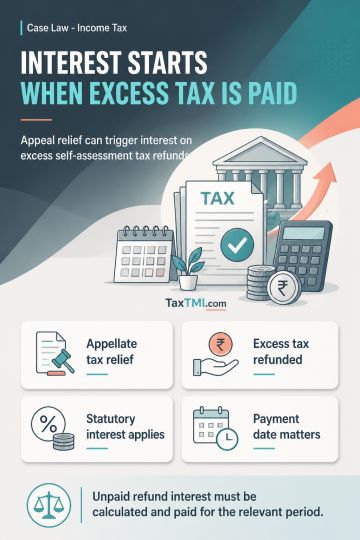
Excess self-assessment tax refunded after appellate relief attracts interest as a statutory, non-discretionary consequence where tax ultimately chargeable is lower than tax paid. Refund entitlement arises when tax deducted at source, advance tax, self-assessment tax, or regular-assessment tax exceeds the final annual tax liability following appeal or other proceedings. Where prescribed computation categories do not govern, interest on excess tax runs from the payment date. Unpaid interest on the resulting refund must be determined and paid for the relevant period, including up to the point at which interest had already been granted.
Excess self-assessment tax refunded after appellate relief attracts interest as a statutory, non-discretionary consequence where tax ultimately chargeable is lower than tax paid. Refund entitlement arises when tax deducted at source, advance tax, self-assessment tax, or regular-assessment tax exceeds the final annual tax liability following appeal or other proceedings. Where prescribed computation categories do not govern, interest on excess tax runs from the payment date. Unpaid interest on the resulting refund must be determined and paid for the relevant period, including up to the point at which interest had already been granted.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4897