Foundational assessment satisfaction is essential before initiating penalty for cash receipt of immovable-property sale consideration under section 27...
Tax collection at source on purchases removes duplicate withholding obligation, while trade-creditor evidence requires verification before unexplained...
Transfer-pricing comparability requires material turnover effects; adjustments must cover only associated-enterprise transactions and exclude abnormal...
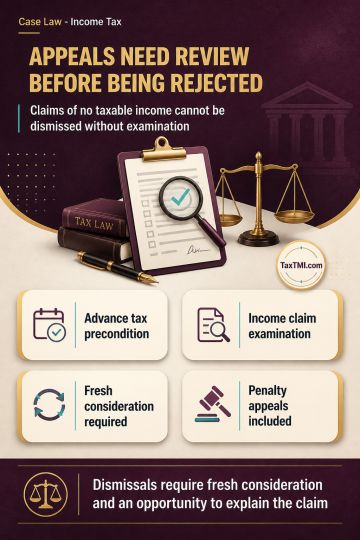
Advance-tax payment otherwise payable is a precondition to admission of an income-tax appeal where no return of income has been filed, unless exemption is sought and granted for good and sufficient reason. A claimed absence of taxable income and corresponding advance-tax liability requires examination where neither the taxpayer nor the Assessing Officer has computed the liability; it cannot be rejected summarily merely because no exemption application was filed. Dismissal for non-compliance in those circumstances requires fresh consideration with an opportunity to explain the claim. Penalty appeals concerning under-reporting of income and audit default, where based on the same admission objection, follow the same treatment.
Advance-tax payment otherwise payable is a precondition to admission of an income-tax appeal where no return of income has been filed, unless exemption is sought and granted for good and sufficient reason. A claimed absence of taxable income and corresponding advance-tax liability requires examination where neither the taxpayer nor the Assessing Officer has computed the liability; it cannot be rejected summarily merely because no exemption application was filed. Dismissal for non-compliance in those circumstances requires fresh consideration with an opportunity to explain the claim. Penalty appeals concerning under-reporting of income and audit default, where based on the same admission objection, follow the same treatment.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4931