Opportunity to furnish unsecured-loan confirmations is required before reassessment initiation; proceedings require fresh consideration after taxpayer...
Under-reporting on a first reassessment return attracts penalty, while enhanced misreporting penalty requires proof of a statutory misreporting catego...
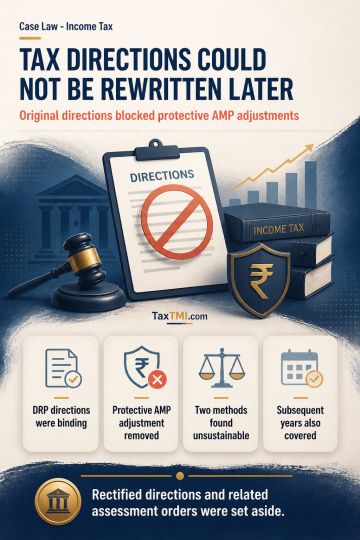
Rectification of DRP directions that changed AMP benchmarking from the earlier approach to intensity-adjusted TNMM, on the CIT(DR)'s application, was unsustainable; the rectified directions and consequential assessment order were set aside. Original DRP directions requiring deletion of a protective AMP adjustment bound the assessment proceedings, so the protective adjustment based on the Bright Line Test was also set aside. AMP transfer-pricing adjustments derived through both the Bright Line Test and intensity-adjusted TNMM were unsustainable for the relevant year and corresponding subsequent years. The impugned assessment orders were set aside, while academic, consequential and unpressed grounds remained open or were not pressed.
Rectification of DRP directions that changed AMP benchmarking from the earlier approach to intensity-adjusted TNMM, on the CIT(DR)'s application, was unsustainable; the rectified directions and consequential assessment order were set aside. Original DRP directions requiring deletion of a protective AMP adjustment bound the assessment proceedings, so the protective adjustment based on the Bright Line Test was also set aside. AMP transfer-pricing adjustments derived through both the Bright Line Test and intensity-adjusted TNMM were unsustainable for the relevant year and corresponding subsequent years. The impugned assessment orders were set aside, while academic, consequential and unpressed grounds remained open or were not pressed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4916