Provisional attachment fails without material showing likely concealment, transfer, or dealing that could frustrate confiscation of mortgaged property...
Works-contract goods transfers remain outside service tax, while qualifying lift irrigation works receive exemption and extended limitation cannot app...
Customs assessment information portal centralises rulings and guidance to promote consistent classification, valuation, transparency and informed comp...
Composite show-cause notices spanning multiple financial years are jurisdictionally invalid, allowing writ review despite an alternative appellate rem...
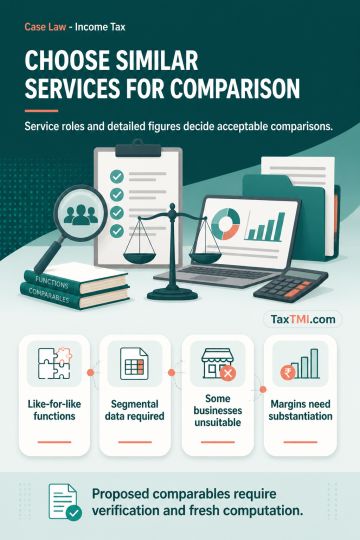
Transfer-pricing benchmarking for administrative and marketing...
Functional comparability governs selection of support-service and IT-enabled service comparables, with verification required for unresolved data and margin issues.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Transfer-pricing benchmarking for administrative and marketing support services requires functional similarity and adequate segmental data. Engineering consultancy, construction-related activities, trading and mixed sales-service operations, commission agency and technical services are unsuitable comparables; a different financial year alone does not require exclusion where an appropriate adjustment is possible. For IT-enabled services, outsourcing businesses without segmental information and knowledge-process outsourcing providers are functionally dissimilar. Proposed comparables needing review of segmental or financial data, including those affected by a service-income filter, require verification and fresh computation. Claimed comparable-margin corrections and risk adjustments depend on substantiation, factual reconciliation and consequential examination.
Transfer-pricing benchmarking for administrative and marketing support services requires functional similarity and adequate segmental data. Engineering consultancy, construction-related activities, trading and mixed sales-service operations, commission agency and technical services are unsuitable comparables; a different financial year alone does not require exclusion where an appropriate adjustment is possible. For IT-enabled services, outsourcing businesses without segmental information and knowledge-process outsourcing providers are functionally dissimilar. Proposed comparables needing review of segmental or financial data, including those affected by a service-income filter, require verification and fresh computation. Claimed comparable-margin corrections and risk adjustments depend on substantiation, factual reconciliation and consequential examination.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4891