Departmental appeal limitation after call-book recall preserves original filing, while documented correlation supports SAD refund on imported granules...
Income-tax prosecution fails when appellate remand removes its factual foundation; directors require company arraignment for vicarious criminal liabil...
Capital character of assignment consideration prevents taxation as residuary income, while unsupported interest-related expenditure remains non-deduct...
Make-available condition shields regional support-service receipts from Indian taxation where no independent capability or permanent establishment exi...
Transfer-pricing treatment of corporate guarantees and convertible loans followed prior-year consistency, with taxable foreign dividends excluded from...
Transfer-pricing benchmarking confines adjustments to associated-enterprise transactions and integrates delayed receivables through TNMM working-capit...
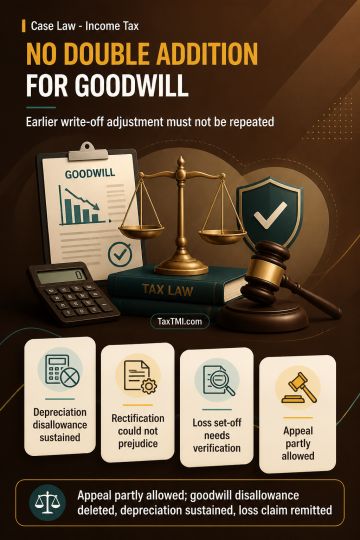
Goodwill write-off already added back in computing taxable income should not be added again in assessment; an ambiguous rectification that potentially disallows goodwill beyond withdrawal of consequential depreciation cannot prejudice the assessee. The further goodwill disallowance was deleted, while the depreciation disallowance was sustained on the assessee's concession. A claim for set-off of brought-forward business losses requires verification of its quantum and eligibility from earlier-year records where it has not been adjudicated. That claim was remitted to the AO for verification and lawful set-off after reasonable opportunity. The appeal was partly allowed for statistical purposes.
Goodwill write-off already added back in computing taxable income should not be added again in assessment; an ambiguous rectification that potentially disallows goodwill beyond withdrawal of consequential depreciation cannot prejudice the assessee. The further goodwill disallowance was deleted, while the depreciation disallowance was sustained on the assessee's concession. A claim for set-off of brought-forward business losses requires verification of its quantum and eligibility from earlier-year records where it has not been adjudicated. That claim was remitted to the AO for verification and lawful set-off after reasonable opportunity. The appeal was partly allowed for statistical purposes.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4896