Belated Form 10B filing during Covid-19 cannot defeat charitable exemption where genuine hardship warrants condonation and substantial justice prevail...
Limitation for consequential assessments runs from prescribed authority receipt, while verified purchases cannot be disallowed merely for unanswered s...
Higher depreciation for qualifying commercial vehicles, exempt-income disallowance, research deduction verification, and club-expense treatment clarif...
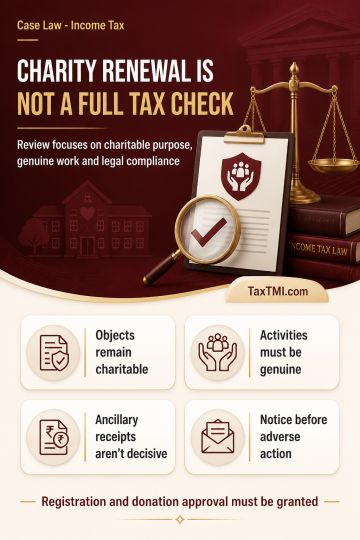
Charitable registration renewal cannot become an assessment of receipts, profitability or annual exemption compliance, requiring renewal and donation ...
Page of 4891
Press 'Enter' after typing page number.
1781 to 1800 of 97820 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
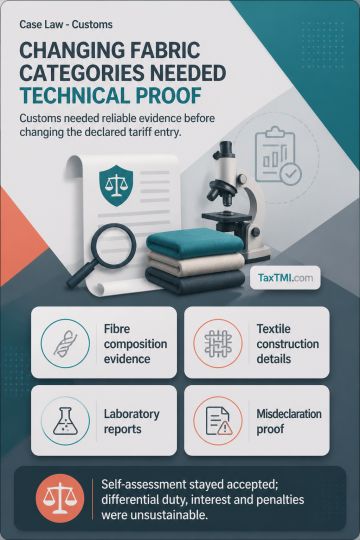
Customs reclassification of mixed-fibre polyester warp knitted fabrics requires Revenue to establish, through cogent technical evidence, that the declared residual classification is incorrect. Fibre composition and textile construction under Chapter 60 cannot be determined solely from commercial documents, visual examination, or a generic polyester description. Where samples, laboratory reports, and evidence of misdeclaration or suppression are absent, an accepted self-assessment cannot be reopened or replaced with multiple alternative tariff entries. Classification under Customs Tariff Item 6005 9000 and the related concessional basic customs duty benefit therefore remained available, and the differential duty, interest, and penalties were unsustainable.
Customs reclassification of mixed-fibre polyester warp knitted fabrics requires Revenue to establish, through cogent technical evidence, that the declared residual classification is incorrect. Fibre composition and textile construction under Chapter 60 cannot be determined solely from commercial documents, visual examination, or a generic polyester description. Where samples, laboratory reports, and evidence of misdeclaration or suppression are absent, an accepted self-assessment cannot be reopened or replaced with multiple alternative tariff entries. Classification under Customs Tariff Item 6005 9000 and the related concessional basic customs duty benefit therefore remained available, and the differential duty, interest, and penalties were unsustainable.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4891