Constitutional personal-liberty safeguards limit PMLA twin bail conditions where completed investigations lead to prolonged incarceration before trial...
Automated airline software subscriptions without human intervention fail technical-services characterisation and do not make available underlying tech...
Business support recruitment and training receipts qualify for presumptive business taxation, not professional taxation under technical consultancy ru...
Treaty exemption for foreign permanent-establishment management fees prevailed, while dividend expense disallowance remained limited to an accepted al...
Centralised assessment transfers: participation after requesting centralisation can bar technical jurisdictional challenges, while assessment disputes...
Binding precedent remains operative despite pending challenge, supporting deletion of interest disallowance when debt is converted into preference sha...
Page of 4912
Press 'Enter' after typing page number.
121 to 140 of 98239 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
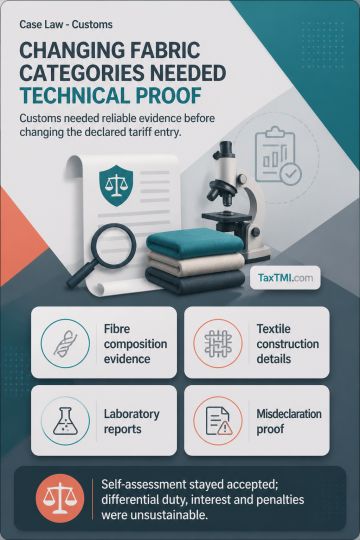
Customs reclassification of mixed-fibre polyester warp knitted fabrics requires Revenue to establish, through cogent technical evidence, that the declared residual classification is incorrect. Fibre composition and textile construction under Chapter 60 cannot be determined solely from commercial documents, visual examination, or a generic polyester description. Where samples, laboratory reports, and evidence of misdeclaration or suppression are absent, an accepted self-assessment cannot be reopened or replaced with multiple alternative tariff entries. Classification under Customs Tariff Item 6005 9000 and the related concessional basic customs duty benefit therefore remained available, and the differential duty, interest, and penalties were unsustainable.
Customs reclassification of mixed-fibre polyester warp knitted fabrics requires Revenue to establish, through cogent technical evidence, that the declared residual classification is incorrect. Fibre composition and textile construction under Chapter 60 cannot be determined solely from commercial documents, visual examination, or a generic polyester description. Where samples, laboratory reports, and evidence of misdeclaration or suppression are absent, an accepted self-assessment cannot be reopened or replaced with multiple alternative tariff entries. Classification under Customs Tariff Item 6005 9000 and the related concessional basic customs duty benefit therefore remained available, and the differential duty, interest, and penalties were unsustainable.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4912