Preliminary reassessment proceedings generally require statutory remedies unless jurisdiction is wholly absent or mandatory conditions are patently br...
Agricultural land classification requires cumulative factual indicators, while industrial-purpose land and absent agricultural use defeat reinvestment...
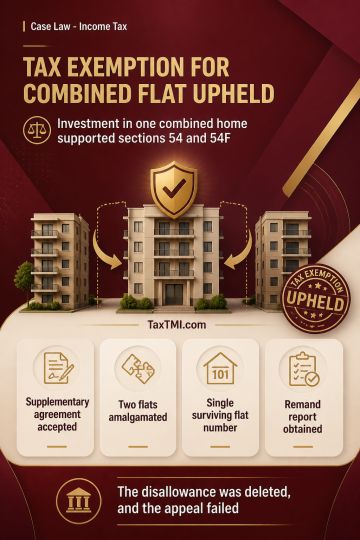
Composite residential flat exemption upheld where supplementary agreement merged adjoining units and additional evidence supported the taxpayer's inve...
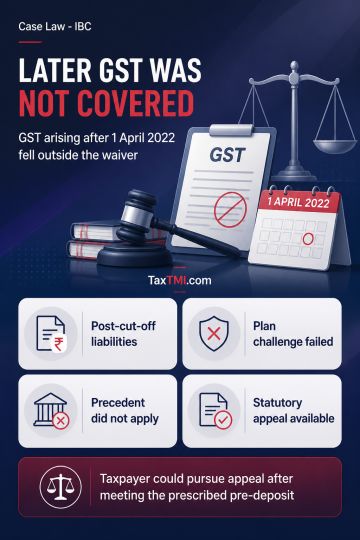
Approved insolvency resolution plan waivers of indirect-tax liabilities did not extend to GST liabilities arising after 1 April 2022. The cited Supreme Court precedent on the binding effect of resolution plans was inapplicable on the stated facts, while a High Court ruling was identified as clarifying the position. The challenge based on the resolution plan was not accepted; the taxpayer could pursue the statutory appeal on meeting the prescribed pre-deposit requirement.
Approved insolvency resolution plan waivers of indirect-tax liabilities did not extend to GST liabilities arising after 1 April 2022. The cited Supreme Court precedent on the binding effect of resolution plans was inapplicable on the stated facts, while a High Court ruling was identified as clarifying the position. The challenge based on the resolution plan was not accepted; the taxpayer could pursue the statutory appeal on meeting the prescribed pre-deposit requirement.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4894