External development charges trigger TDS under section 194C, while disputed administrative payments require factual verification and fresh adjudicatio...
Section 270AA penalty immunity requires identified statutory defaults and a hearing before rejection; reassessment disclosure may constitute under-rep...
Section 80JJAA employee-cost deduction allowed for deployed staff but barred against transfer-pricing income enhancement, with pricing issues remanded...
Transfer-pricing methodology protects commercially genuine associated-enterprise payments, while pre-2016 secondary adjustments and related notional i...
Negative liens over operating assets can constitute international transactions requiring arm's-length pricing reflecting restricted borrowing and expa...
Cross-examination rights in Customs Broker revocation inquiries require witness examination; procedural denial may be cured through fresh adjudication...
Banks may identify and report suspicious transactions but cannot...
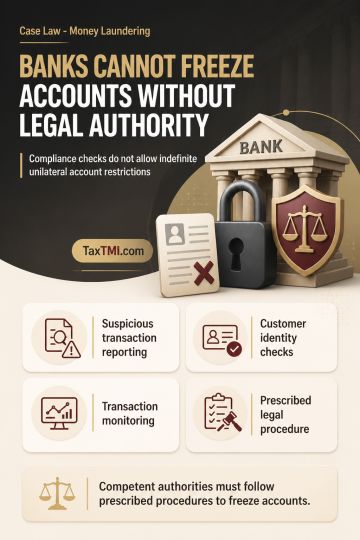
Bank account freezing requires statutory authority; anti-money-laundering compliance and KYC monitoring do not permit unilateral indefinite restrictions.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Banks may identify and report suspicious transactions but cannot unilaterally freeze customer accounts without statutory authority. Section 12AA of the Prevention of Money Laundering Act permits identity verification, record examination and information requisition as compliance measures; it does not grant investigative or adjudicatory powers to freeze accounts. RBI KYC Directions similarly require customer due diligence, information collection, transaction monitoring and regulatory reporting, rather than indefinite freezing based solely on transaction volume. Property attachment and account-freezing powers lie with competent authorities acting under prescribed legal procedure.
Banks may identify and report suspicious transactions but cannot unilaterally freeze customer accounts without statutory authority. Section 12AA of the Prevention of Money Laundering Act permits identity verification, record examination and information requisition as compliance measures; it does not grant investigative or adjudicatory powers to freeze accounts. RBI KYC Directions similarly require customer due diligence, information collection, transaction monitoring and regulatory reporting, rather than indefinite freezing based solely on transaction volume. Property attachment and account-freezing powers lie with competent authorities acting under prescribed legal procedure.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4888