Educational approval requires mandatory State registration, but incidental surplus and trustee-owned land do not prove private benefit or profit motiv...
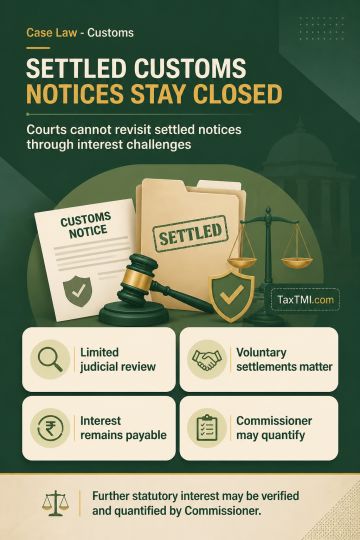
Judicial review of settlement orders cannot reopen settled customs notices, while statutory interest remains subject to verification and quantificatio...
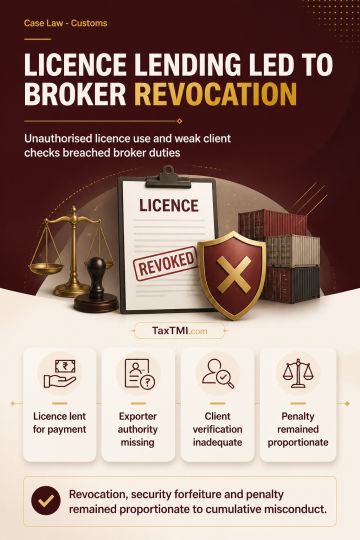
Customs Broker licence lending for consideration justified revocation where exporter authorisation and client verification obligations were also breac...
Fraudulent import documents suspend limitation protection, while redemption of confiscated goods requires duty and interest despite bona fide purchase...
Best-judgment assessment of security agency service value must rest on actual, verifiable records and a rational nexus to services and consideration, rather than assumed growth or earlier peak turnover; unsupported demands require fresh determination. Receipts must be examined transaction-wise to exclude legally exempt, non-taxable and genuine reimbursable amounts, subject after amendment to pure-agent conditions. Export and SEZ exemptions require examination of transactional evidence, not rejection solely for missing documents. CENVAT credit cannot be denied merely because salary expenditure predominates; admissibility requires record-based verification. Extended limitation requires deliberate evasion and is unavailable for disclosed audited records, subject in any event to the five-year outer limit. Parallel proceedings must not produce duplicate demand or recovery; remand must exclude transactions already determined.
Best-judgment assessment of security agency service value must rest on actual, verifiable records and a rational nexus to services and consideration, rather than assumed growth or earlier peak turnover; unsupported demands require fresh determination. Receipts must be examined transaction-wise to exclude legally exempt, non-taxable and genuine reimbursable amounts, subject after amendment to pure-agent conditions. Export and SEZ exemptions require examination of transactional evidence, not rejection solely for missing documents. CENVAT credit cannot be denied merely because salary expenditure predominates; admissibility requires record-based verification. Extended limitation requires deliberate evasion and is unavailable for disclosed audited records, subject in any event to the five-year outer limit. Parallel proceedings must not produce duplicate demand or recovery; remand must exclude transactions already determined.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4897