Delayed-payment surcharge is not taxable tolerance consideration where it penalises default, while meter testing follows electricity distribution trea...
Works-contract goods transfers remain outside service tax, while qualifying lift irrigation works receive exemption and extended limitation cannot app...
Governmental authority status supports construction-service exemption, while pre-cutoff contract and stamp-duty compliance requires verification on re...
Original works exemption excludes standalone boulder transportation, leaving subcontracted railway-project transport services subject to service tax l...
Development rights transfers treated as immovable property, while construction abatement applies and repeated non-payment permits extended service-tax...
Page of 481
Press 'Enter' after typing page number.
1 to 20 of 9619 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
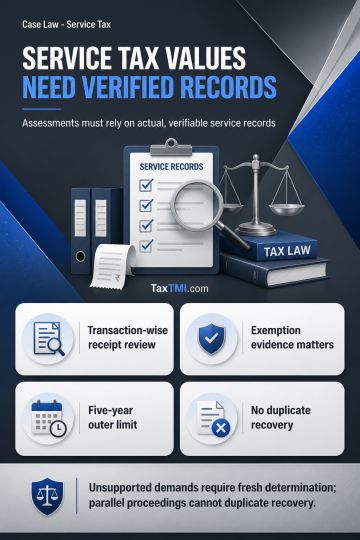
Best-judgment assessment of security agency service value must rest on actual, verifiable records and a rational nexus to services and consideration, rather than assumed growth or earlier peak turnover; unsupported demands require fresh determination. Receipts must be examined transaction-wise to exclude legally exempt, non-taxable and genuine reimbursable amounts, subject after amendment to pure-agent conditions. Export and SEZ exemptions require examination of transactional evidence, not rejection solely for missing documents. CENVAT credit cannot be denied merely because salary expenditure predominates; admissibility requires record-based verification. Extended limitation requires deliberate evasion and is unavailable for disclosed audited records, subject in any event to the five-year outer limit. Parallel proceedings must not produce duplicate demand or recovery; remand must exclude transactions already determined.
Best-judgment assessment of security agency service value must rest on actual, verifiable records and a rational nexus to services and consideration, rather than assumed growth or earlier peak turnover; unsupported demands require fresh determination. Receipts must be examined transaction-wise to exclude legally exempt, non-taxable and genuine reimbursable amounts, subject after amendment to pure-agent conditions. Export and SEZ exemptions require examination of transactional evidence, not rejection solely for missing documents. CENVAT credit cannot be denied merely because salary expenditure predominates; admissibility requires record-based verification. Extended limitation requires deliberate evasion and is unavailable for disclosed audited records, subject in any event to the five-year outer limit. Parallel proceedings must not produce duplicate demand or recovery; remand must exclude transactions already determined.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI