Pre-amendment reassessment limitation bars late notices under the preserved regime, invalidating consequential reassessment for affected earlier asses...
Cash-sales explanations for bank deposits require documentary reconciliation; reassessment notice survived where effective response time was available...
Functional comparability in transfer pricing prevents ad hoc arm's length adjustments where functions, assets, risks and reliable comparables are unes...
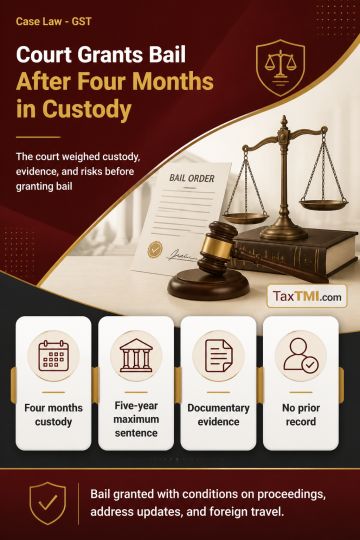
Regular bail in alleged fraudulent input tax credit availment through fake invoices depends on more than the seriousness of an economic offence. Relevant considerations include custody period, maximum punishment, the nature of evidence, risk of evidence tampering or witness influence, cooperation with trial, prior antecedents, and the likelihood of early trial completion. The High Court found that the accused had spent about four months in custody, faced a maximum five-year sentence, had no antecedents, and confronted documentary evidence, with no material showing interference risk. Bail was granted on bonds, subject to conditions against interfering with proceedings, requiring address updates, and restricting foreign travel without permission.
Regular bail in alleged fraudulent input tax credit availment through fake invoices depends on more than the seriousness of an economic offence. Relevant considerations include custody period, maximum punishment, the nature of evidence, risk of evidence tampering or witness influence, cooperation with trial, prior antecedents, and the likelihood of early trial completion. The High Court found that the accused had spent about four months in custody, faced a maximum five-year sentence, had no antecedents, and confronted documentary evidence, with no material showing interference risk. Bail was granted on bonds, subject to conditions against interfering with proceedings, requiring address updates, and restricting foreign travel without permission.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918