Charitable trust registration requires a specified-violation notice; settled cash deposits and related-party payments did not justify cancellation or ...
External development charges trigger TDS under section 194C, while disputed administrative payments require factual verification and fresh adjudicatio...
Section 270AA penalty immunity requires identified statutory defaults and a hearing before rejection; reassessment disclosure may constitute under-rep...
Section 80JJAA employee-cost deduction allowed for deployed staff but barred against transfer-pricing income enhancement, with pricing issues remanded...
Transfer-pricing methodology protects commercially genuine associated-enterprise payments, while pre-2016 secondary adjustments and related notional i...
Negative liens over operating assets can constitute international transactions requiring arm's-length pricing reflecting restricted borrowing and expa...
Cross-examination rights in Customs Broker revocation inquiries require witness examination; procedural denial may be cured through fresh adjudication...
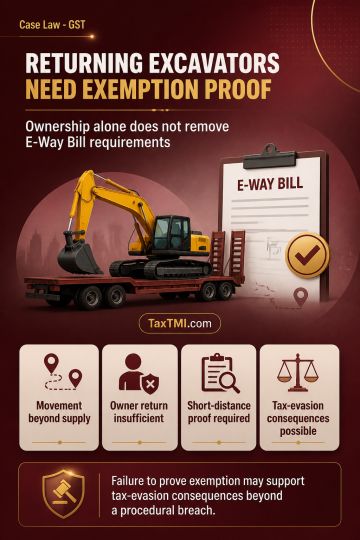
E-Way Bill requirements extend to movement of goods for reasons other than supply, including return of an excavator from a work site to registered premises. Ownership and return to the owner's premises do not independently remove that requirement. A short-distance exemption must be established with satisfactory evidence that the movement falls within Rule 138(14) or an applicable notification. Failure to prove the exemption, or to clarify the tax treatment of consideration for use of the equipment, may prevent the breach from being treated as merely procedural and may support tax-evasion consequences under CGST/UPGST enforcement provisions.
E-Way Bill requirements extend to movement of goods for reasons other than supply, including return of an excavator from a work site to registered premises. Ownership and return to the owner's premises do not independently remove that requirement. A short-distance exemption must be established with satisfactory evidence that the movement falls within Rule 138(14) or an applicable notification. Failure to prove the exemption, or to clarify the tax treatment of consideration for use of the equipment, may prevent the breach from being treated as merely procedural and may support tax-evasion consequences under CGST/UPGST enforcement provisions.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4910