TNMM functional comparability requires excluding rice manufacturers from a pure Basmati rice trader's benchmark and recognising operating export recei...
Working-capital adjustment subsumes delayed-receivable effects in TNMM benchmarking of captive software-development services, avoiding separate notion...
Transfer-pricing comparability requires exclusion of financially illogical super-profit comparables and correction of unsupported annual-report and ma...
Charitable character assessment preserves Section 80G approval despite inclusive spiritual teachings and incidental religious expenditure within the s...
Penalty proceedings for cash-loan acceptance require assessment proceedings and recorded Assessing Officer satisfaction; absent these, the proceedings...
Functional comparability governs software-service benchmarking: dissimilar companies are excluded, while related-party filters, margins and working-ca...
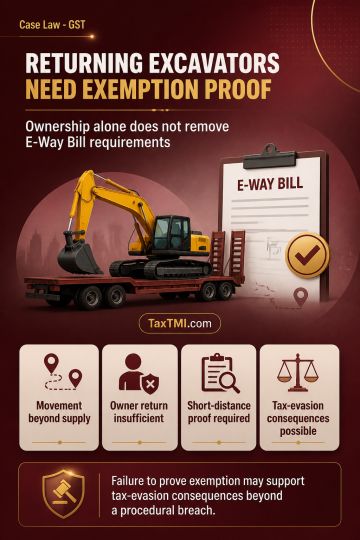
E-Way Bill requirements extend to movement of goods for reasons other than supply, including return of an excavator from a work site to registered premises. Ownership and return to the owner's premises do not independently remove that requirement. A short-distance exemption must be established with satisfactory evidence that the movement falls within Rule 138(14) or an applicable notification. Failure to prove the exemption, or to clarify the tax treatment of consideration for use of the equipment, may prevent the breach from being treated as merely procedural and may support tax-evasion consequences under CGST/UPGST enforcement provisions.
E-Way Bill requirements extend to movement of goods for reasons other than supply, including return of an excavator from a work site to registered premises. Ownership and return to the owner's premises do not independently remove that requirement. A short-distance exemption must be established with satisfactory evidence that the movement falls within Rule 138(14) or an applicable notification. Failure to prove the exemption, or to clarify the tax treatment of consideration for use of the equipment, may prevent the breach from being treated as merely procedural and may support tax-evasion consequences under CGST/UPGST enforcement provisions.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4905