Head Office cost allocation requires prescribed transfer-pricing methods; treaty ceilings bar surcharge and cess, while duplicate taxation is excluded...
Cost-to-cost reimbursement of seconded employees is not service consideration; transfer-pricing markup was deleted and amalgamation amortisation allow...
Crystallisation of liability supports prior-period expense deduction, while functionally distinct divisions require separate transfer-pricing benchmar...
Functional comparability under TNMM requires transaction-specific FAR analysis before benchmarking business-support services provided to associated en...
Page of 4908
Press 'Enter' after typing page number.
121 to 140 of 98141 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
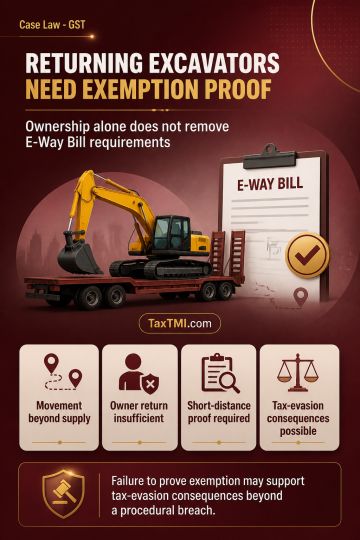
E-Way Bill requirements extend to movement of goods for reasons other than supply, including return of an excavator from a work site to registered premises. Ownership and return to the owner's premises do not independently remove that requirement. A short-distance exemption must be established with satisfactory evidence that the movement falls within Rule 138(14) or an applicable notification. Failure to prove the exemption, or to clarify the tax treatment of consideration for use of the equipment, may prevent the breach from being treated as merely procedural and may support tax-evasion consequences under CGST/UPGST enforcement provisions.
E-Way Bill requirements extend to movement of goods for reasons other than supply, including return of an excavator from a work site to registered premises. Ownership and return to the owner's premises do not independently remove that requirement. A short-distance exemption must be established with satisfactory evidence that the movement falls within Rule 138(14) or an applicable notification. Failure to prove the exemption, or to clarify the tax treatment of consideration for use of the equipment, may prevent the breach from being treated as merely procedural and may support tax-evasion consequences under CGST/UPGST enforcement provisions.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4908