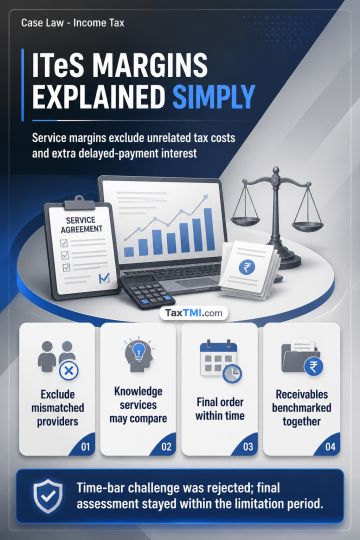
Transfer-pricing treatment of ITeS margins excludes pass-through tax recoveries and separate delayed-receivables interest after working-capital adjust...
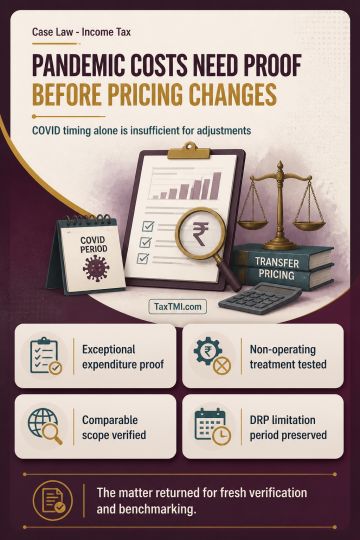
Capacity-utilisation adjustments under TNMM can neutralise substantiated COVID-related idle costs where underutilisation materially affects profitabil...
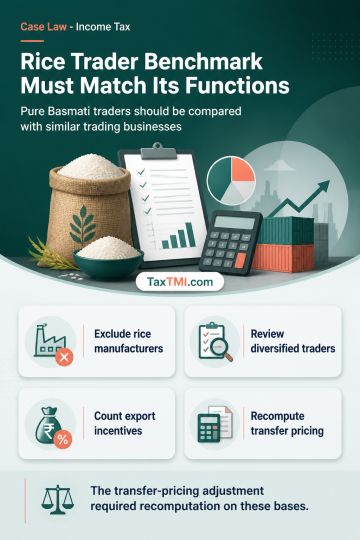
TNMM functional comparability requires excluding rice manufacturers from a pure Basmati rice trader's benchmark and recognising operating export recei...
Working-capital adjustment subsumes delayed-receivable effects in TNMM benchmarking of captive software-development services, avoiding separate notion...
Page of 4929
Press 'Enter' after typing page number.
2181 to 2200 of 98580 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
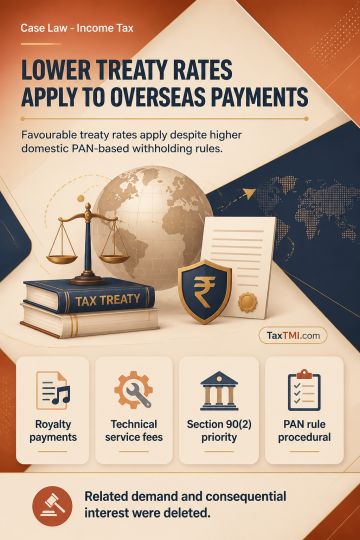
Beneficial DTAA withholding rates apply to royalty and fees for technical services paid to non-residents where those rates are more favourable than domestic law. Section 90(2) gives treaty provisions priority in such circumstances. The higher tax-deduction requirement for non-furnishing of PAN under section 206AA is procedural and does not override the applicable beneficial treaty rate. Accordingly, tax deducted at the relevant DTAA rate does not create a short-deduction liability merely because the PAN-based domestic withholding rate is higher; the related demand and consequential interest were deleted.
Beneficial DTAA withholding rates apply to royalty and fees for technical services paid to non-residents where those rates are more favourable than domestic law. Section 90(2) gives treaty provisions priority in such circumstances. The higher tax-deduction requirement for non-furnishing of PAN under section 206AA is procedural and does not override the applicable beneficial treaty rate. Accordingly, tax deducted at the relevant DTAA rate does not create a short-deduction liability merely because the PAN-based domestic withholding rate is higher; the related demand and consequential interest were deleted.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4929