Disciplinary proportionality requires penalties for Authorised Representative misconduct to match proven harm, leading to reconsideration of registrat...
Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
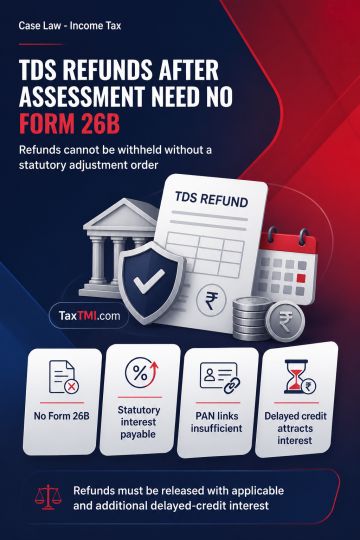
Refunds arising from TDS assessments under section 201 or appellate orders constitute crystallised entitlements payable with statutory interest, without requiring Form 26B. Section 200A, Rule 31A and Form 26B govern CPC processing and adjustment of TDS before assessment and do not apply to post-assessment refunds. Such refunds may be withheld or set off against outstanding demands only through a statutory adjustment order under section 245; demands linked to the taxpayer's PAN or related TANs alone do not justify withholding. The Department was directed to release the refunds with applicable interest, with additional interest for delayed credit.
Refunds arising from TDS assessments under section 201 or appellate orders constitute crystallised entitlements payable with statutory interest, without requiring Form 26B. Section 200A, Rule 31A and Form 26B govern CPC processing and adjustment of TDS before assessment and do not apply to post-assessment refunds. Such refunds may be withheld or set off against outstanding demands only through a statutory adjustment order under section 245; demands linked to the taxpayer's PAN or related TANs alone do not justify withholding. The Department was directed to release the refunds with applicable interest, with additional interest for delayed credit.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918