Pre-amendment reassessment limitation bars late notices under the preserved regime, invalidating consequential reassessment for affected earlier asses...
Cash-sales explanations for bank deposits require documentary reconciliation; reassessment notice survived where effective response time was available...
Functional comparability in transfer pricing prevents ad hoc arm's length adjustments where functions, assets, risks and reliable comparables are unes...
Contingency expenses, exempt-income disallowance, and royalty benchmarking: unsupported adjustments were deleted under consistent accounting and trans...
Section 148A requires the assessee to receive information...
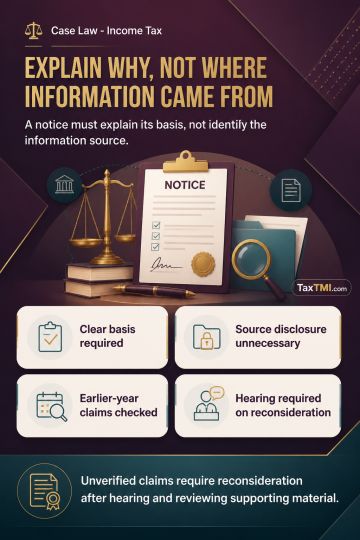
Reassessment disclosure requirements permit stated reasons without revealing information sources, but prior-taxation claims require full examination before orders.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Section 148A requires the assessee to receive information suggesting income has escaped assessment, not the source of that information. Particulars in the annexure to a reassessment show-cause notice may satisfy this requirement where they identify the basis and reasons sufficiently for a response; non-disclosure of an audit objection does not invalidate the notice. However, where an assessee asserts that a taxable marked-to-market hedge-reserve amount was included in an earlier year, the assessing authority must verify that claim and its consequences. Failure to do so requires reconsideration after hearing the assessee, including additional supporting material.
Section 148A requires the assessee to receive information suggesting income has escaped assessment, not the source of that information. Particulars in the annexure to a reassessment show-cause notice may satisfy this requirement where they identify the basis and reasons sufficiently for a response; non-disclosure of an audit objection does not invalidate the notice. However, where an assessee asserts that a taxable marked-to-market hedge-reserve amount was included in an earlier year, the assessing authority must verify that claim and its consequences. Failure to do so requires reconsideration after hearing the assessee, including additional supporting material.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918