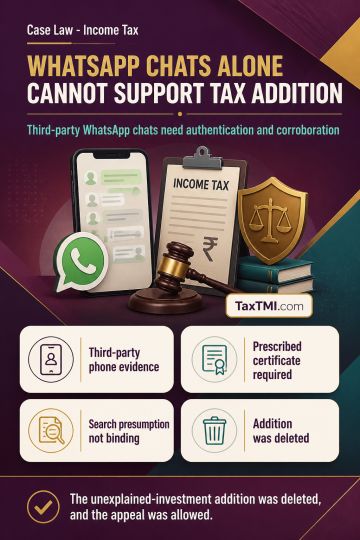
Electronic WhatsApp evidence without authentication or independent corroboration cannot sustain an unexplained-investment addition based on third-part...
Mutual current-account transactions excluded from deemed dividend treatment where no fresh borrowing arose; unsupported unsecured-loan addition also f...
Interest on borrowings used to acquire plant, machinery, scrap, land and buildings held as current assets for sale in an asset-trading business is revenue expenditure. The proviso to section 36(1)(iii), which restricts interest deduction until an acquired asset is first put to use, does not apply where the assets are acquired solely for resale and are neither intended nor required to be used in manufacturing. Borrowings for buying and selling such assets are for business purposes. Acquisition-related expenses incurred in dealing in current assets for sale are likewise revenue expenditure allowable under section 37(1), rather than capital expenditure.
Interest on borrowings used to acquire plant, machinery, scrap, land and buildings held as current assets for sale in an asset-trading business is revenue expenditure. The proviso to section 36(1)(iii), which restricts interest deduction until an acquired asset is first put to use, does not apply where the assets are acquired solely for resale and are neither intended nor required to be used in manufacturing. Borrowings for buying and selling such assets are for business purposes. Acquisition-related expenses incurred in dealing in current assets for sale are likewise revenue expenditure allowable under section 37(1), rather than capital expenditure.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4886