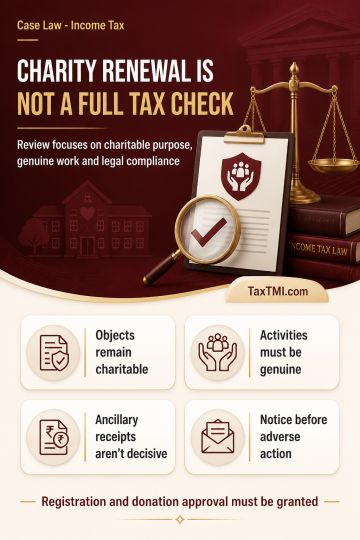
Charitable registration renewal cannot become an assessment of receipts, profitability or annual exemption compliance, requiring renewal and donation ...
AMP expenditure for own business is not an international transaction without an associated-enterprise arrangement, eliminating transfer pricing adjust...
Customs valuation must use comparable contemporary imports, while confiscation fines and penalties require proportionate recalculation on reassessed v...
Depositor-protection proceedings prevail over corporate insolvency, while liquidators may recover chit receivables using copies of seized company reco...
Intermediary service classification fails where overseas admission facilitation is supplied independently, preserving export treatment and small-provi...
Satellite transponder bandwidth is telecommunication, not Business Support Service; foreign non-telegraph providers triggered no service tax liability...
Page of 4897
Press 'Enter' after typing page number.
1901 to 1920 of 97923 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
Reverse-charge liability on foreign or intermediary bank charges deducted while transmitting export proceeds requires a taxable service provider-recipient relationship. Where the exporter neither engaged the banks nor owed them consideration, deductions from export proceeds do not establish that relationship and do not attract service tax under Banking and Other Financial Services. Regulatory dossier preparation and compilation for overseas pharmaceutical approvals must be classified by the activity actually performed, not the provider's technical qualifications. Preparing documentation from available information or published literature, without advice or scientific or technical assistance, is not Scientific or Technical Consultancy Service. The related service-tax demands, interest and penalties were unsustainable.
Reverse-charge liability on foreign or intermediary bank charges deducted while transmitting export proceeds requires a taxable service provider-recipient relationship. Where the exporter neither engaged the banks nor owed them consideration, deductions from export proceeds do not establish that relationship and do not attract service tax under Banking and Other Financial Services. Regulatory dossier preparation and compilation for overseas pharmaceutical approvals must be classified by the activity actually performed, not the provider's technical qualifications. Preparing documentation from available information or published literature, without advice or scientific or technical assistance, is not Scientific or Technical Consultancy Service. The related service-tax demands, interest and penalties were unsustainable.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4897