Opportunity to furnish unsecured-loan confirmations is required before reassessment initiation; proceedings require fresh consideration after taxpayer...
Under-reporting on a first reassessment return attracts penalty, while enhanced misreporting penalty requires proof of a statutory misreporting catego...
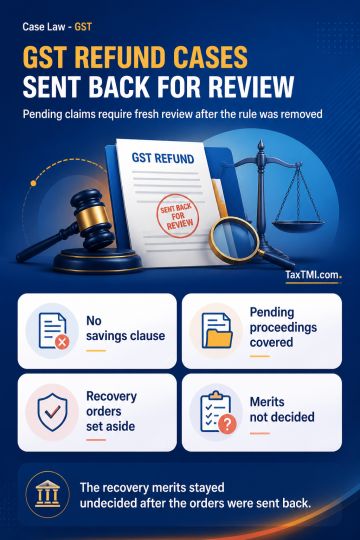
Omission of Rule 96(10) of the Central Goods and Services Tax Rules, 2017, without a savings clause was treated as applying to pending refund-recovery proceedings. Applying the Supreme Court pronouncement on the effect of such omission, the High Court set aside the refund-recovery orders and remanded the matters for fresh consideration under that principle. The merits of the refund-recovery claims were not decided.
Omission of Rule 96(10) of the Central Goods and Services Tax Rules, 2017, without a savings clause was treated as applying to pending refund-recovery proceedings. Applying the Supreme Court pronouncement on the effect of such omission, the High Court set aside the refund-recovery orders and remanded the matters for fresh consideration under that principle. The merits of the refund-recovery claims were not decided.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915