Transfer pricing comparability prioritises reliable external CUPs and foreign-currency LIBOR benchmarks for exports, borrowings and delayed receivable...
Section 153C satisfaction and seized electronic records sustained unexplained-investment addition, subject to proportionate ownership-share verificati...
Natural justice in insolvency-professional discipline requires disclosed material; notices based on extraneous material and ignored defences are vitia...
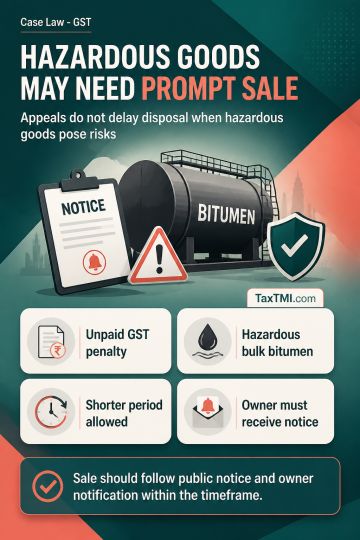
Section 129(6) of the GST Acts requires detained goods to be sold or otherwise disposed of to recover an unpaid penalty after the prescribed period. Its proviso permits a shorter period where goods are perishable, hazardous or likely to depreciate. Inflammable bulk bitumen qualifies as hazardous goods, so the continuing availability of an appeal does not displace the obligation to initiate disposal where risk to the goods and conveyance warrants prompt action. Sale should proceed through public notice, with notice to the owner, within the stipulated timeframe.
Section 129(6) of the GST Acts requires detained goods to be sold or otherwise disposed of to recover an unpaid penalty after the prescribed period. Its proviso permits a shorter period where goods are perishable, hazardous or likely to depreciate. Inflammable bulk bitumen qualifies as hazardous goods, so the continuing availability of an appeal does not displace the obligation to initiate disposal where risk to the goods and conveyance warrants prompt action. Sale should proceed through public notice, with notice to the owner, within the stipulated timeframe.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4891