Service of notice and contractual debt acknowledgment preserved insolvency admission against a corporate guarantor despite limitation and natural just...
Original works exemption excludes standalone boulder transportation, leaving subcontracted railway-project transport services subject to service tax l...
Annual production capacity determinations excluding stenter galleries support refunds for unconstitutional excise levies without an unjust-enrichment ...
Vicarious liability for cheque dishonour requires specific allegations of responsibility and cheque signatory; generic director allegations cannot sus...
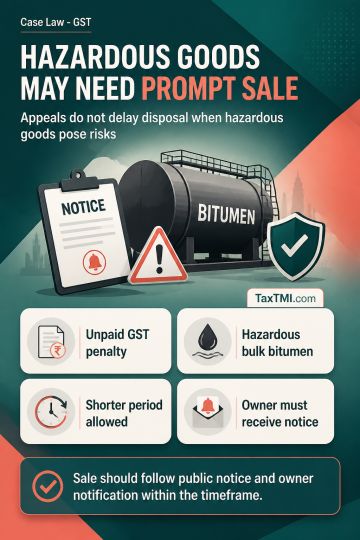
Section 129(6) of the GST Acts requires detained goods to be sold or otherwise disposed of to recover an unpaid penalty after the prescribed period. Its proviso permits a shorter period where goods are perishable, hazardous or likely to depreciate. Inflammable bulk bitumen qualifies as hazardous goods, so the continuing availability of an appeal does not displace the obligation to initiate disposal where risk to the goods and conveyance warrants prompt action. Sale should proceed through public notice, with notice to the owner, within the stipulated timeframe.
Section 129(6) of the GST Acts requires detained goods to be sold or otherwise disposed of to recover an unpaid penalty after the prescribed period. Its proviso permits a shorter period where goods are perishable, hazardous or likely to depreciate. Inflammable bulk bitumen qualifies as hazardous goods, so the continuing availability of an appeal does not displace the obligation to initiate disposal where risk to the goods and conveyance warrants prompt action. Sale should proceed through public notice, with notice to the owner, within the stipulated timeframe.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4891