Service of notice and contractual debt acknowledgment preserved insolvency admission against a corporate guarantor despite limitation and natural just...
Original works exemption excludes standalone boulder transportation, leaving subcontracted railway-project transport services subject to service tax l...
Annual production capacity determinations excluding stenter galleries support refunds for unconstitutional excise levies without an unjust-enrichment ...
Vicarious liability for cheque dishonour requires specific allegations of responsibility and cheque signatory; generic director allegations cannot sus...
IT Resilience Index requires market infrastructure institutions to automate resilience scoring, early warnings, and continuous service-delivery monito...
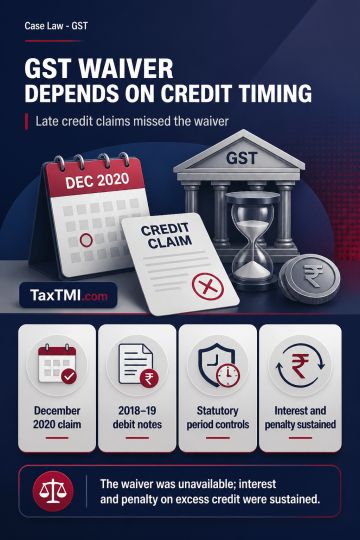
GST amnesty waiver eligibility for interest and penalty depends on the disputed input tax credit being availed within the prescribed statutory period, rather than on the financial year in which the underlying debit notes were issued. Excess credit first claimed in the December 2020 return fell outside the scheme's temporal scope despite its connection with debit notes from 2018-19. Guidance or decisions concerning input tax credit mismatch reconciliation cannot extend an expressly limited statutory period. The waiver was unavailable, and the interest and penalty on the excess credit claim were sustained.
GST amnesty waiver eligibility for interest and penalty depends on the disputed input tax credit being availed within the prescribed statutory period, rather than on the financial year in which the underlying debit notes were issued. Excess credit first claimed in the December 2020 return fell outside the scheme's temporal scope despite its connection with debit notes from 2018-19. Guidance or decisions concerning input tax credit mismatch reconciliation cannot extend an expressly limited statutory period. The waiver was unavailable, and the interest and penalty on the excess credit claim were sustained.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4888