Form 26AS evidence requires successor-entity accounting verification after business transfer, while invoice-supported related-party advertising expend...
Money-laundering judgment timing requires awaiting the scheduled-offence decision despite continuation of the underlying trial where outcomes directly...
Accredited investor eligibility expands through securities-market exposure, while alternative investment fund disputes require prescribed resolution a...
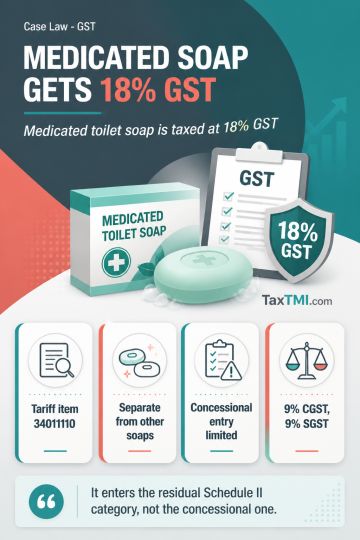
Medicated Toilet Soap is classified under tariff item 34011110, separate from other toilet soaps classified under tariff item 34011190. The revised GST notification adopts the Customs Tariff nomenclature and interpretative rules. The concessional Schedule I entry for toilet soap applies only to products under tariff item 34011190 and does not extend to Medicated Toilet Soap. Medicated Toilet Soap therefore falls under the residual Schedule II entry and attracts GST at 18% (9% CGST and 9% SGST).
Medicated Toilet Soap is classified under tariff item 34011110, separate from other toilet soaps classified under tariff item 34011190. The revised GST notification adopts the Customs Tariff nomenclature and interpretative rules. The concessional Schedule I entry for toilet soap applies only to products under tariff item 34011190 and does not extend to Medicated Toilet Soap. Medicated Toilet Soap therefore falls under the residual Schedule II entry and attracts GST at 18% (9% CGST and 9% SGST).
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915